eHealth Devices Market Size & Growth Forecast 2027–2036, By Segments (Type), Regional Demand Trends (North America, Asia Pacific, Europe), Key Country Insights (U.S., Japan, South Korea, Germany, France, Italy), and Competitive Landscape
Jump to Content
Market Size and Growth Outlook
eHealth Devices Market size was more than USD 22.17 billion in 2026 and is set to grow at a 8.93% CAGR between 2027 and 2036, surpassing USD 52.15 billion by 2036. The industry revenue for 2027 is calculated at USD 23.84 billion.
Get more details on this report
Request Free Sample ReporteHealth Devices Market Intelligence Snapshot
Regional Market Dynamics
- North America captured 41.34% of the market in 2026 due to widespread connected healthcare infrastructure, strong remote monitoring adoption, and extensive use of digital health tools across care settings.
- Asia Pacific is expected to grow at a 10.74% CAGR, driven by expanding digital healthcare access, increasing demand for portable monitoring devices, and broader adoption of connected health solutions.
Segment Momentum
- Glucose meters lead with a 36.04% share due to routine diabetes monitoring needs, frequent testing behavior, and strong integration into both homecare and clinical chronic disease management workflows.
- Blood pressure meters are the fastest-growing segment as consumers adopt regular at-home cardiovascular monitoring, supported by preventive care trends and expanding use of connected remote health tracking systems.
Market Expansion Drivers
- Rising chronic diseases prevalence driving continuous remote patient monitoring device adoption globally.
- Integration of IoT and AI enabling connected home healthcare monitoring ecosystems.
- Growing government digital health initiatives improving accessibility of eHealth monitoring devices.
Leading Market Participants
- Leading companies in the ehealth devices market include Abbott Laboratories (United States), Medtronic plc (Ireland), DexCom, Inc. (United States), Omron Corporation (Japan), F. Hoffmann-La Roche AG (Switzerland), PHC Holdings Corporation (Japan), Doro AB (Sweden), Koninklijke Philips N.V. (Netherlands).
Global Market Forecast Snapshot
Market Outlook
- 2026 Market Size: USD 22.17 billion
- 2027 Estimated Market Size: USD 23.84 billion.
- Projected Market Size: USD 52.15 billion by 2036
- Growth Forecast: 8.93% CAGR (2027-2036)
Regional and Segment Outlook
- Leading Regional Market: North America
- High-Growth Regional Hub: Asia Pacific
- Core Revenue Segment: Glucose Meters (Type)
- Emerging Opportunity Segment: Blood Pressure Meters (Type)
Market Growth Drivers and Industry Trends
Rising chronic diseases prevalence driving continuous remote patient monitoring device adoption globally
The growing burden of chronic conditions such as cardiovascular diseases, diabetes, and respiratory disorders is increasing the need for regular health assessment outside traditional clinical settings, which will drive the ehealth devices market growth. Patients requiring long-term disease management are increasingly using connected monitoring devices to track vital health parameters continuously and share readings with healthcare professionals. These solutions can support earlier identification of changes in patient conditions, reduce dependence on frequent hospital visits, and enable personalized follow-up care. The convenience of home-based monitoring is particularly valuable for individuals managing persistent conditions that require repeated measurements and ongoing clinical oversight.
Integration of IoT and AI enabling connected home healthcare monitoring ecosystems
The convergence of internet of things connectivity and artificial intelligence is transforming standalone health devices into interconnected monitoring ecosystems, strengthening demand across the ehealth devices market. IoT-enabled devices can collect and transmit patient-generated health information, while AI-based analytics can process these data streams to identify unusual patterns and support clinical decision-making. Integration with smartphones, cloud platforms, and remote care systems also enables healthcare providers to access patient information without requiring physical consultations for every routine assessment. Such capabilities are supporting the development of connected home healthcare environments in which multiple devices can contribute to broader patient monitoring and individualized care management.
Growing government digital health initiatives improving accessibility of eHealth monitoring devices
Government efforts to expand digital healthcare infrastructure and improve access to technology-enabled medical services are creating favorable conditions for wider adoption of ehealth monitoring solutions. The ehealth devices market benefits as public healthcare programs increasingly emphasize remote consultations, electronic health information exchange, and digitally supported disease management. Investments in digital health infrastructure can also improve connectivity between patients, healthcare providers, and monitoring platforms, particularly where access to conventional healthcare facilities is limited. Broader policy support for technology-enabled care is encouraging healthcare systems to incorporate connected monitoring devices into routine patient management.
| Growth Driver | Impact on CAGR | Regulatory Influence | Geographic Relevance | Adoption Rate | Impact Timeline |
|---|---|---|---|---|---|
| Rising chronic diseases prevalence driving continuous remote patient monitoring device adoption globally | 2.30% | Moderate | North America, Europe, Asia Pacific | High | Near Term |
| Integration of IoT and AI enabling connected home healthcare monitoring ecosystems | 2.00% | Moderate | North America, Europe, Asia Pacific | High | Mid Term |
| Growing government digital health initiatives improving accessibility of eHealth monitoring devices | 1.60% | High | Asia Pacific, Latin America | Medium | Mid Term |
Explore Growth Opportunities
Request Free Sample ReportRegional Demand Dynamics
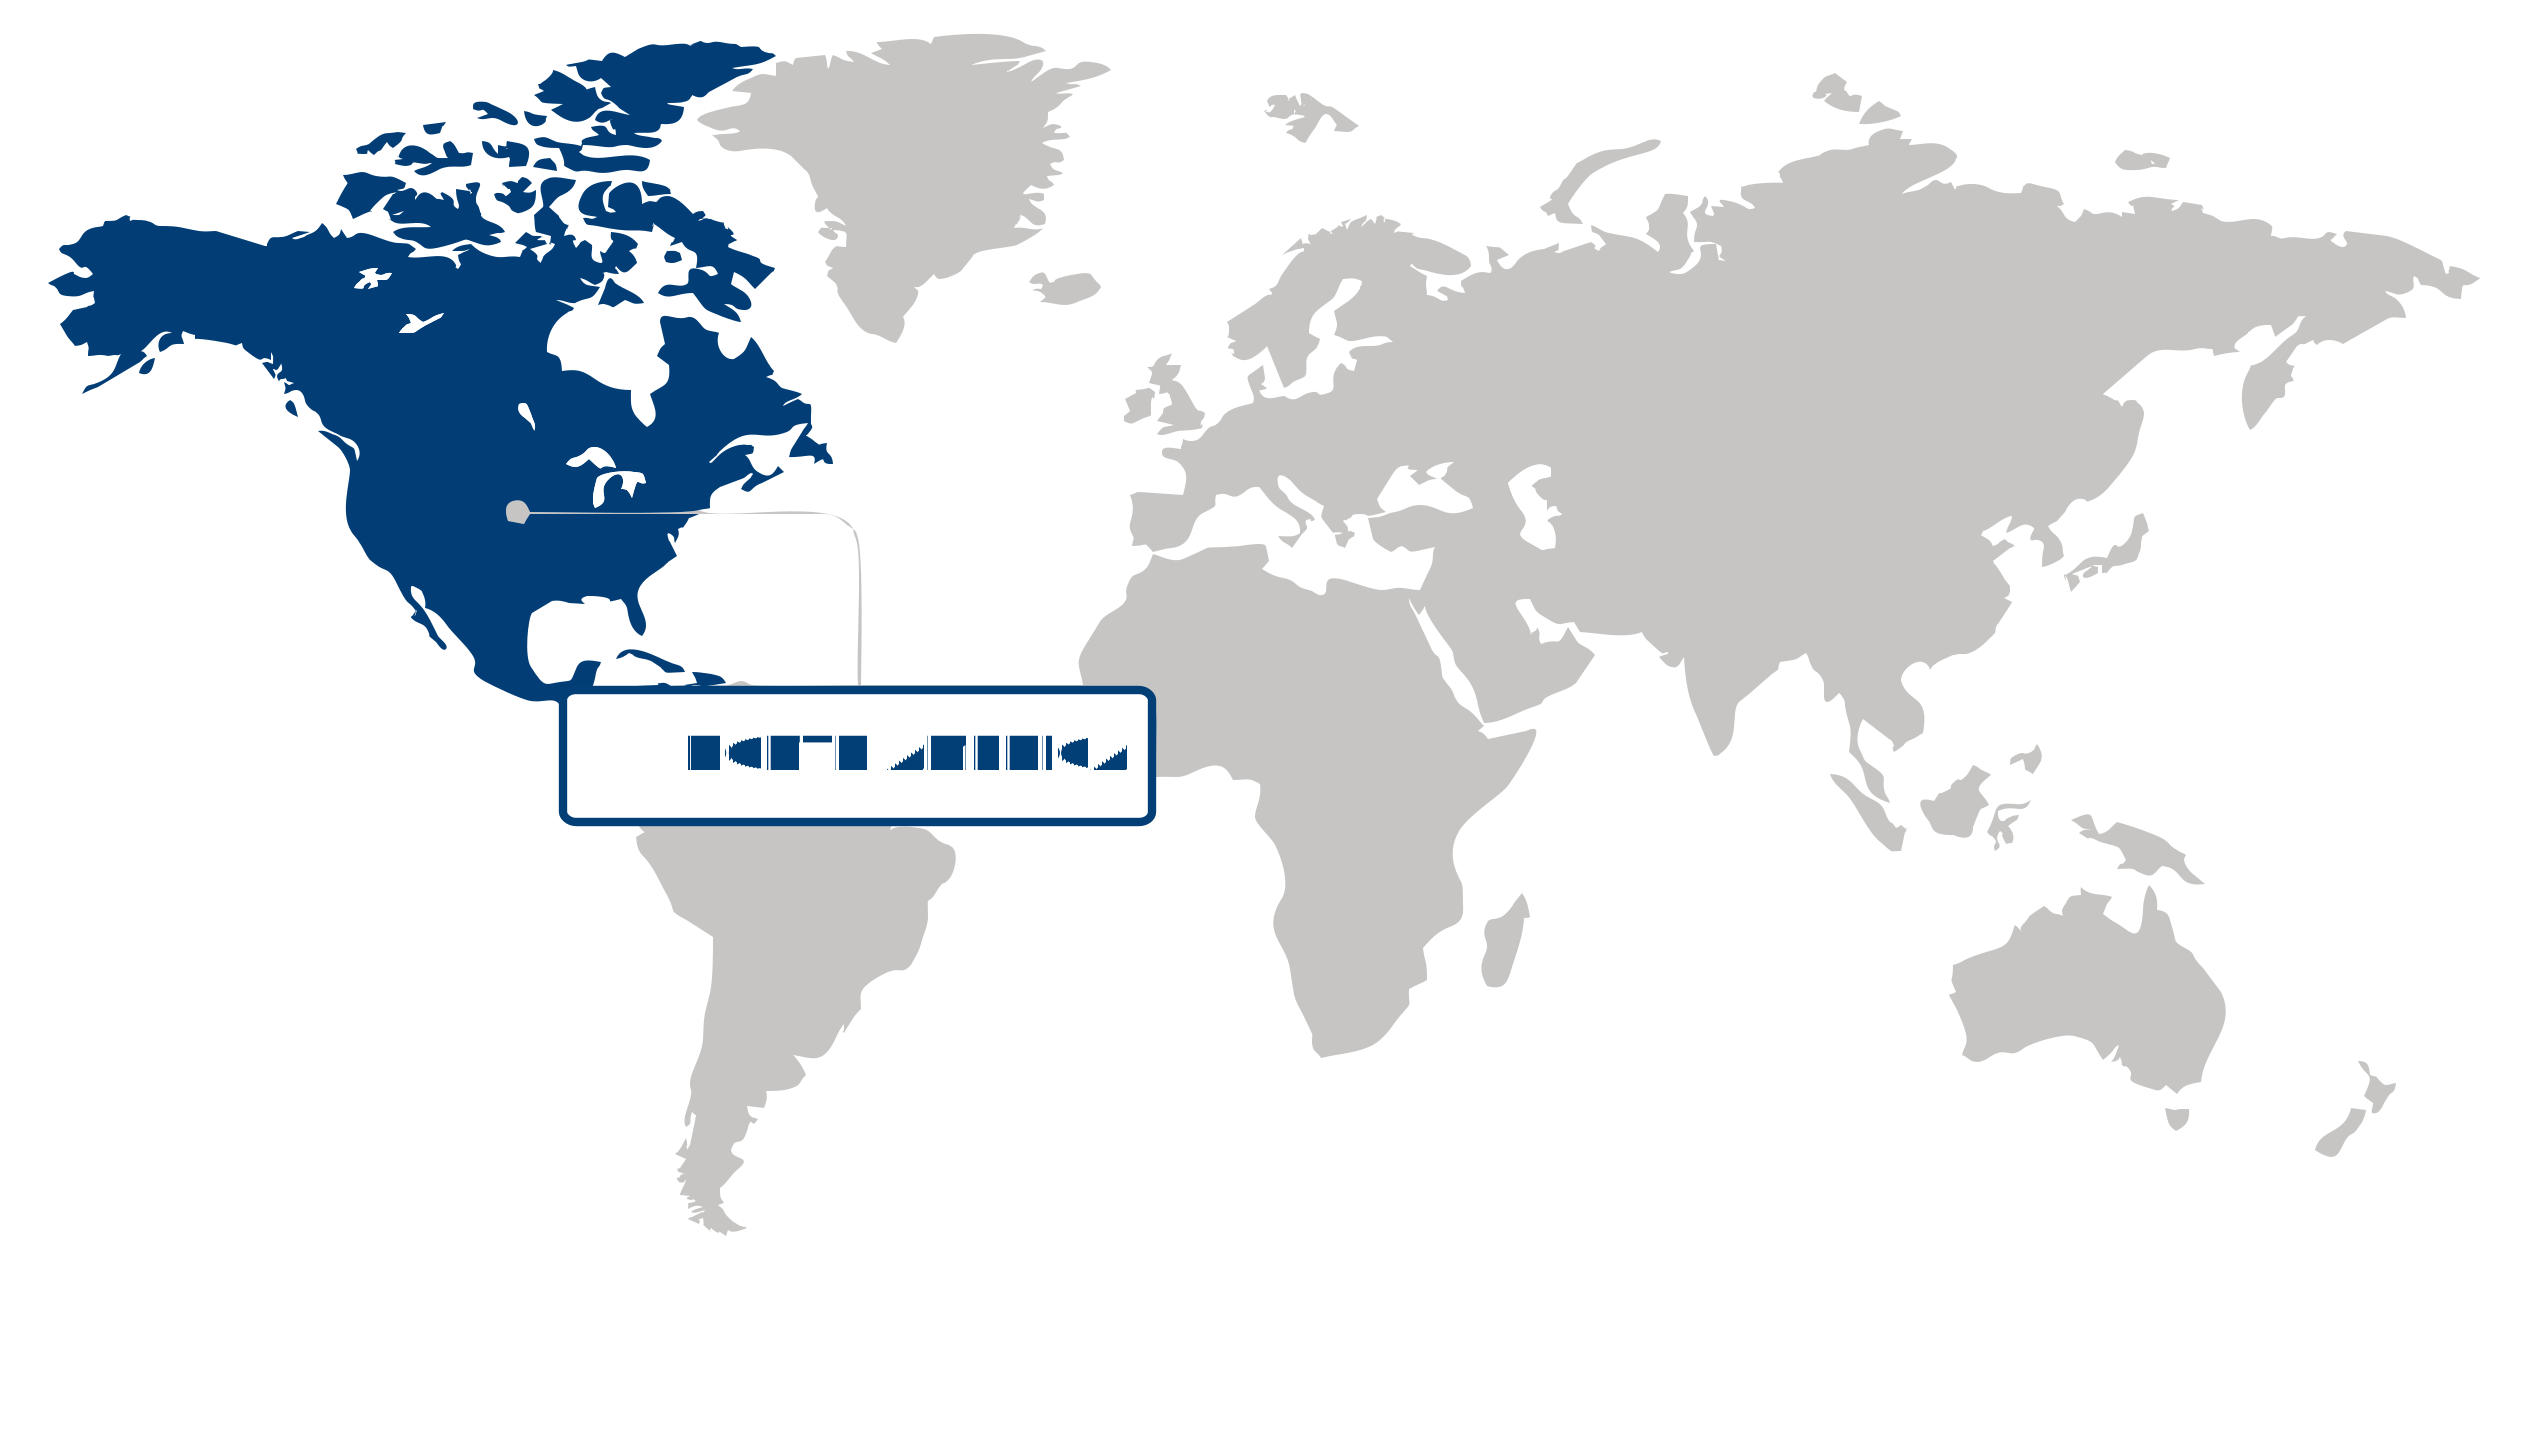
North America (Largest Region)
North America held the largest share of the ehealth devices market, accounting for 41.34% in 2026, supported by advanced healthcare infrastructure, strong adoption of connected medical technologies, and growing emphasis on remote and preventive care. Healthcare providers and consumers are increasingly incorporating wearable monitors, connected diagnostic devices, and digitally enabled patient-management tools into routine healthcare practices. Favorable reimbursement environments, established digital health ecosystems, and high awareness of continuous health monitoring further strengthen regional demand. The integration of ehealth devices with electronic health records, mobile health platforms, and data analytics is also improving clinical decision-making and patient engagement. At the same time, regulatory requirements surrounding device safety, interoperability, cybersecurity, and patient data protection continue to influence product development and purchasing decisions.
Asia Pacific (Fastest-Growing Region)
Asia Pacific is emerging as the fastest-growing regional market, driven by expanding healthcare access, increasing digitalization, and rising demand for convenient and affordable health-monitoring solutions. Growing investments in healthcare infrastructure are creating opportunities for connected devices across hospitals, clinics, home healthcare, and remote patient monitoring applications. The increasing penetration of smartphones and digital health platforms is also supporting wider consumer acceptance of wearable and portable medical technologies. In addition, the need to manage chronic conditions and improve healthcare delivery across large and diverse populations is encouraging providers to adopt technologies capable of supporting decentralized care. Increasing technological capabilities, healthcare modernization initiatives, and greater awareness of preventive health are expected to reinforce the region's expansion.
| Parameter | North America | Asia Pacific | Europe | Latin America | MEA |
|---|---|---|---|---|---|
| Innovation HubiScaleNascentDeveloping Advanced | |||||
| Cost-Sensitive RegioniScaleLowMedium High | |||||
| Regulatory EnvironmentiScaleRestrictiveNeutral Supportive | |||||
| Demand DriversiScaleWeakModerate Strong | |||||
| Development StageiScaleEmergingDeveloping Developed | |||||
| Adoption RateiScaleLowMedium High | |||||
| New Entrants / StartupsiScaleSparseModerate Dense | |||||
| Macro IndicatorsiScaleWeakStable Strong |
Key Country Insights
Germany 🇩🇪
Clinical Monitoring IntegrationGermany is strengthening the use of ehealth devices through digital healthcare initiatives and reimbursement support for remote monitoring. Demand in Germany is centered on clinically validated devices that can securely connect with healthcare information systems.
France 🇫🇷
Preventive Health MonitoringFrance is emphasizing ehealth devices that facilitate chronic disease management and preventive healthcare programs. Regulatory attention on digital health solutions is encouraging adoption of connected monitoring tools across both clinical and home-care environments.
Italy 🇮🇹
Home Care ConnectivityItaly is seeing increased demand for ehealth devices that support remote monitoring and decentralized healthcare delivery. Healthcare organizations in Italy are focusing on technologies that improve patient follow-up and extend care services beyond traditional clinical settings.
Japan 🇯🇵
Aging Population SupportJapan is deploying ehealth devices to address healthcare needs associated with an aging population and rising demand for home-based care. The market favors user-friendly monitoring technologies that enable continuous health tracking and reduce pressure on care facilities.
South Korea 🇰🇷
Digital Health EcosystemSouth Korea is integrating ehealth devices with advanced mobile health platforms and telemedicine services. Consumers and healthcare providers in South Korea are increasingly adopting connected devices that support preventive care and real-time health monitoring.
United States 🇺🇸
Connected Care ExpansionThe U.S. ehealth devices market is advancing through broader adoption of remote patient monitoring and connected wearable technologies. Healthcare providers are increasingly integrating device-generated data into care pathways to improve chronic disease management and patient engagement.
eHealth Devices Market Share (%), by Type, 2026
Go beyond the chart, access full insights & data tables
Request Free Sample ReportType Segment Analysis: Glucose Meters (Largest Segment) vs Blood Pressure Meters (Fastest-Growing Segment)
Glucose meters dominated the ehealth devices market with a 36.04% share in 2026. Their leading position reflects the widespread need for regular glucose monitoring among individuals managing diabetes and those requiring ongoing metabolic assessment. Increasing emphasis on self-monitoring and home-based disease management is encouraging the use of connected and easy-to-operate glucose devices, while digital data capture and integration with broader healthcare workflows are improving the value of these devices for both patients and healthcare professionals.
Blood pressure meters are expected to achieve the fastest growth as hypertension and cardiovascular risk management receive greater attention across preventive and chronic care settings. Consumers increasingly seek convenient devices that allow blood pressure measurements to be performed outside clinical facilities, supporting more frequent monitoring and earlier identification of abnormal readings. The expansion of remote patient monitoring and connected healthcare is further strengthening demand for digital blood pressure devices that can facilitate data sharing and ongoing clinical oversight.
| Segment | Sub-Segment | Largest Segment | Fastest Growing |
|---|---|---|---|
| Type | Blood Pressure Meters, Fever Meters, Glucose Meters, Care Phone/Social Alarms | Glucose Meters | Blood Pressure Meters |
Unlock insights tailored to your business with our bespoke market research solutions.
Click to get your customized report now.
Competitive Landscape and Market Positioning
Major players in the ehealth devices market:
1. Abbott Laboratories (United States)
2. Medtronic plc (Ireland)
3. DexCom Inc. (United States)
4. Omron Corporation (Japan)
5. F. Hoffmann-La Roche AG (Switzerland)
6. PHC Holdings Corporation (Japan)
7. Doro AB (Sweden)
8. Koninklijke Philips N.V. (Netherlands)
Digital health monitoring is becoming more integrated with connected care ecosystems. Real-time health tracking and analytics are improving preventive healthcare outcomes. The ehealth devices market is advancing through intelligent wearable and remote monitoring technologies.
| Company | Market Share | Company Revenue | Revenue CAGR (%) | Product Portfolio | Geographic Presence | Innovation / R&D Focus | Strategic Developments |
|---|---|---|---|---|---|---|---|
| Abbott Laboratories (United States) | |||||||
| Medtronic plc (Ireland) | |||||||
| DexCom Inc. (United States) | |||||||
| Omron Corporation (Japan) | |||||||
| F. Hoffmann-La Roche AG (Switzerland) | |||||||
| PHC Holdings Corporation (Japan) | |||||||
| Doro AB (Sweden) | |||||||
| Koninklijke Philips N.V. (Netherlands). |
Industry Development/News
| Company Name | Date | Key Development |
|---|---|---|
| Koninklijke Philips N.V. | Sep-25 | Philips launched a smart telemetry platform for cardiac monitoring designed to enable continuous patient connectivity beyond bedside environments. The development strengthens remote patient monitoring infrastructure and expands clinical data continuity, supporting broader adoption of connected healthcare systems and improving real-time monitoring capabilities across care settings. |
| Koninklijke Philips N.V. | Sep-25 | Philips and Masimo Corporation renewed their innovation partnership to integrate advanced patient monitoring technologies into Philips’ platforms. The collaboration enhances access to physiological measurement capabilities and strengthens interoperability across monitoring systems, reinforcing the ecosystem for advanced hospital and remote patient care solutions. |
| Oracle | Aug-25 | Oracle launched a next-generation AI-driven Oracle Health EHR built on Oracle Cloud Infrastructure. The system is designed to reduce administrative burden and improve clinical workflow intelligence, strengthening digital healthcare infrastructure and enhancing data-driven decision-making capabilities within electronic health record systems. |
| Athenahealth | Aug-25 | Athenahealth introduced major upgrades to its athenaOne platform focused on AI-enabled interoperability and enhanced data exchange. The development improves clinical insights and workflow efficiency for ambulatory care providers, strengthening connectivity across healthcare data systems and supporting broader digital transformation in eHealth platforms. |
| Surescripts | Feb-25 | Surescripts launched Touchless Prior Authorization technology to streamline ePrescribing workflows and reduce administrative delays. The solution enhances automation in payer-provider interactions, improving efficiency in medication approval processes and strengthening digital infrastructure supporting prescription management systems. |
| Allscripts | Oct-19 | Allscripts entered an agreement with Northwell Health to jointly develop an AI-powered next-generation electronic health record system. The collaboration focuses on enhancing clinical decision support and improving data intelligence within EHR systems, strengthening digital healthcare infrastructure and workflow optimization. |
| Cerner Corporation | Jan-19 | Cerner Corporation collaborated with ResMed to integrate Brightree Home Health and Hospice platform with Cerner Millennium EHR. The initiative strengthens interoperability between hospital systems and home care providers, improving continuity of care and enabling more integrated healthcare data exchange across care delivery settings. |
Customize Your Report
Explore examples of how this report can be tailored to different research needs, including custom segments, additional topics or chapters, and related reports. Click a section of the wheel or its numbered marker to explore the available options.
eHealth Devices Market — Custom Segments
| Segment | Sub-Segment |
|---|---|
| Connectivity Technology | Bluetooth, Wi-Fi, Cellular, NFC |
| Care Setting | Home Care, Hospitals & Clinics, Long-Term Care Facilities, Community Care |
| Reimbursement Coverage | Fully Reimbursed, Partially Reimbursed, Self-Pay |
eHealth Devices Market — Custom TOC
| Custom Chapter | Chapter Details |
|---|---|
| Remote Care Ecosystem Assessment |
|
| Data Security & Interoperability Landscape |
|
| Reimbursement & Healthcare Financing Assessment |
|
Need a different cut of the data?
Request Custom ResearchFrequently Asked Questions
What is the market valuation of ehealth devices?
How much is the ehealth devices industry expected to grow by 2036?
How is remote patient monitoring influencing demand across the eHealth devices market?
Why are IoT and AI becoming strategic investment priorities in the eHealth devices market?
Why are glucose meters still the most widely used eHealth devices?
How are blood pressure meters driving new growth in the eHealth devices market?
Why does North America dominate the eHealth devices market?
What factors are accelerating eHealth device adoption in Asia Pacific?
Which companies dominate the ehealth devices landscape?
Our Clients
"The team took the time to understand our specific business needs and delivered a report that was well aligned with our objectives. Their expertise and understanding of the industry were clearly reflected in the quality and relevance of the insights provided."
Siemens Healthcare
"Our experience in acquiring the research report has been excellent. The depth of analysis, and actionable insights provided have been extremely valuable in supporting our ongoing R&D efforts."
GC Biopharma
"The report offered a comprehensive view of the market trends. The in-depth segmentation and analysis of emerging opportunities gave us a better understanding of the market."
Medtronic
Our Research Team & Methodology
Every Fundamental Business Insights report is built by a dedicated vertical research team, validated through a structured primary-and-secondary methodology, and reviewed for accuracy before it reaches you.
This report was prepared by the Healthcare & Medical Devices Research Team at Fundamental Business Insights, a dedicated research group specializing in the global healthcare and medical technology industry. Our analysts continuously monitor advancements in medical technologies, clinical adoption trends, regulatory developments, reimbursement policies, healthcare infrastructure investments, competitive strategies, and evolving patient care requirements to deliver timely and reliable market intelligence. The research is developed using a structured methodology that combines primary discussions with healthcare stakeholders, company financial disclosures, regulatory publications, clinical literature, government healthcare databases, medical associations, and other authoritative secondary sources. Market estimates are validated through multiple research techniques, including top-down and bottom-up analysis, before undergoing an internal quality review to ensure accuracy, consistency, and methodological integrity prior to publication.
Delivery
Published
Available
Support
- Market Size & Forecast
- Market Segmentation
- Regional Analysis
- Growth Drivers & Challenges
- Market Dynamics
- Competitive Landscape
- Company Profiles
- Competitive Benchmarking
- Mergers & Acquisitions
- Market Share Analysis or Key Company Strategies
- Value Chain Analysis
- Porter's Five Forces
- PESTLE Analysis
- Pricing Trends
- Supply-Demand Analysis
- Technology Landscape
- Regulatory Landscape
- Investment & Funding Landscape
- Emerging Opportunities
- Future Market Outlook