mHealth Solutions Market Size & Forecasts 2026-2035, By Segments (Services And Products), Growth Opportunities, Innovation Landscape, Regulatory Shifts, Strategic Regional Insights (U.S., Japan, China, South Korea, UK, Germany, France), and Competitive Dynamics (Apple, Samsung, Philips Healthcare, Cerner, Fitbit)
Jump to Content
Market Size and Growth Outlook
mHealth Solutions Market size is likely to expand from USD 147.93 billion in 2025 to USD 534.15 billion by 2035, posting a CAGR above 13.7% across 2026-2035. The industry’s revenue potential for 2026 is USD 166.04 billion.
Get more details on this report
Request Free Sample ReportmHealth Solutions Market Intelligence Snapshot
Regional Market Dynamics
Segment Momentum
Market Expansion Drivers
Leading Market Participants
Global Market Forecast Snapshot
Market Outlook
Regional and Segment Outlook
Market Growth Drivers and Industry Trends
The accelerating digitization of healthcare and the proliferation of telemedicine are fundamental to the evolution of the mhealth solutions market. Consumer demand for convenient, remote access to healthcare services has soared, fuelled by technological advances and shifting patient preferences, as evidenced by the adoption trends highlighted in Ericsson’s 2023 Mobility Report. The integration of AI-powered diagnostics and real-time health monitoring through smartphones and wearables enhances the market’s value proposition. This digital shift opens strategic opportunities for both incumbent healthcare technology providers and agile startups to innovate patient-centric applications and platforms tailored for diverse demographic groups. Continued advancements in network infrastructure and interoperability indicate sustainable growth, with digital health ecosystems becoming increasingly embedded in routine care delivery.
Expansion of Enterprise mHealth Solutions in Hospitals
Enterprise adoption of mhealth solutions within hospital systems is transforming clinical workflows and patient management, significantly shaping the mhealth solutions market. Leading hospital chains, such as the Mayo Clinic, have publicly endorsed mobile platforms that streamline physician-patient communications and optimize resource allocation. These developments reflect broader workforce trends emphasizing efficiency, data-driven decision-making, and integrated care. Enterprises can leverage this transformation to introduce scalable, secure solutions that align with evolving compliance standards. New entrants can target niche clinical use cases, while established vendors can deepen partnerships with healthcare providers. The ongoing investment in hospital-specific mhealth infrastructures underscores a trend toward comprehensive, enterprise-grade digital health ecosystems.
Government and Insurance Initiatives Supporting mHealth
Targeted government policies and insurance reimbursement models are pivotal growth drivers within the mhealth solutions market, as seen in programs by the U.S. Centers for Medicare & Medicaid Services (CMS) expanding telehealth coverage. These initiatives reduce adoption barriers and incentivize both providers and patients to integrate mhealth tools into standard care pathways. Regulatory clarity and financial support create fertile ground for innovative solutions addressing public health priorities such as chronic disease management and preventive care. Established players benefit from enhanced market acceptance and scale, while newcomers gain entry points through compliance-aligned offerings. The increasing alignment of public health policy with digital health strategies signals a maturation of the mhealth landscape, supporting sustained market expansion.
Industry Restraints:
Data Privacy and Security Concerns
Data privacy and security issues significantly constrain the mHealth solutions market, as consumers and providers contend with complex regulatory landscapes and growing fears of data breaches. The U.S. Federal Trade Commission has consistently highlighted risks associated with unauthorized access to sensitive health information in mobile applications, which undermines patient trust and slows uptake. Operational inefficiencies arise from the need to implement robust encryption, secure authentication, and ongoing compliance monitoring, disproportionately impacting smaller firms with limited resources. For incumbents and startups alike, navigating the Health Insurance Portability and Accountability Act (HIPAA) compliance framework requires costly, time-intensive adjustments that delay product launch and innovation cycles. Given increasing regulatory scrutiny and high-profile cyberattacks, privacy and security requirements will remain a pivotal challenge, compelling market participants to prioritize investments in secure infrastructure and transparent data practices to sustain consumer confidence and foster scalable growth.
Fragmented Regulatory Environments
The highly fragmented regulatory frameworks across regions present a formidable barrier to market expansion for mHealth solutions. For example, the European Union’s Medical Device Regulation (MDR) imposes stringent certification processes distinct from those in the United States overseen by the Food and Drug Administration (FDA), compelling companies to tailor their products and compliance strategies by region. This segmentation raises considerable operational burdens, increasing time-to-market and compliance costs, disproportionately affecting newer entrants lacking established regulatory expertise or financial bandwidth. The Global Digital Health Partnership has documented these challenges, noting that harmonization remains elusive despite ongoing efforts. Strategically, firms must allocate significant resources to local regulatory navigation, limiting their ability to scale rapidly and innovate uniformly. Unless regulatory convergence progresses meaningfully, regional disparities will continue shaping competitive dynamics and market entry strategies in upcoming years.
| Growth Driver | Impact on CAGR | Regulatory Influence | Geographic Relevance | Adoption Rate | Impact Timeline |
|---|---|---|---|---|---|
| Increasing healthcare digitization and telemedicine | 5.00% | Short term (≤ 2 yrs) | North America, Europe | Medium | Fast |
| Expansion of enterprise mHealth solutions in hospitals | 4.50% | Medium term (2–5 yrs) | Europe, Asia Pacific | Medium | Moderate |
| Government and insurance initiatives supporting mHealth | 4.20% | Long term (5+ yrs) | North America, Asia Pacific | High | Slow |
Unlock insights tailored to your business with our bespoke market research solutions.
Click to get your customized report now.
Regional Demand Dynamics
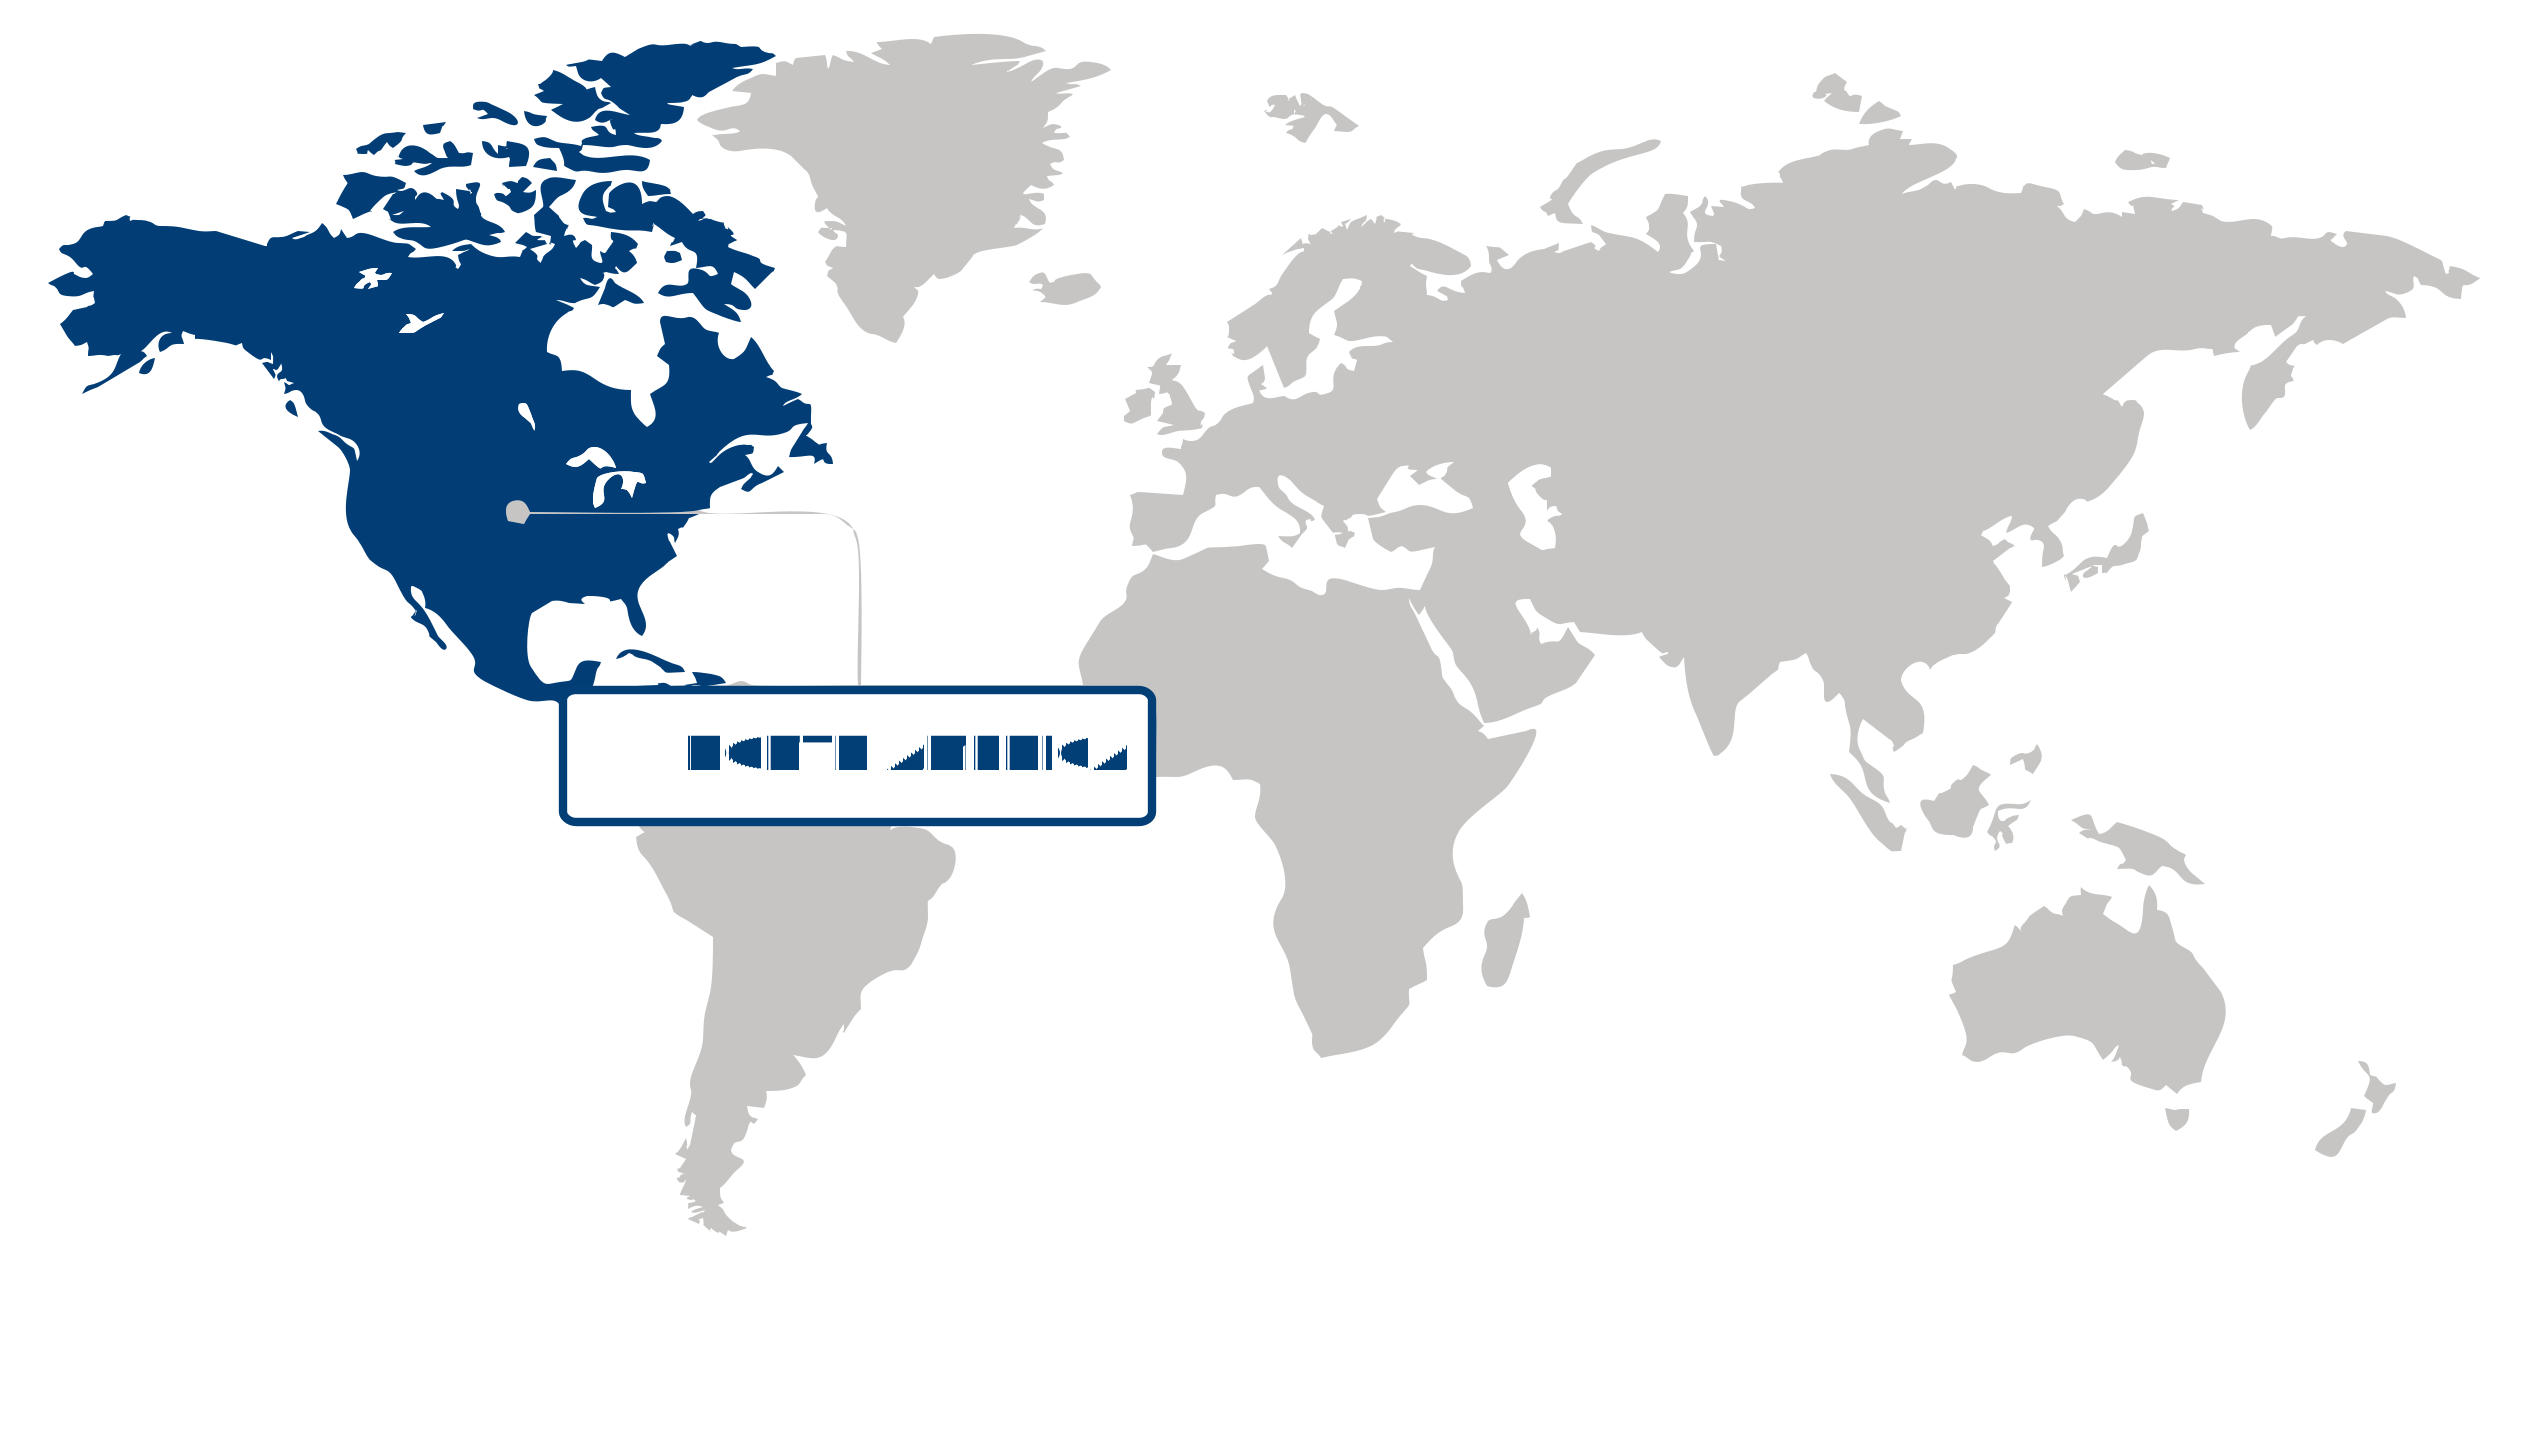
North America captured over 38.2% of the global mhealth solutions market in 2025, establishing it as the largest regional player. This leadership is driven primarily by favorable regulatory policies and robust government campaigns promoting digital health adoption. The region benefits from an advanced healthcare infrastructure and heightened consumer enthusiasm for digital interventions that improve access and efficiency. Initiatives like the U.S. Health and Human Services’ Digital Health Innovation Action Plan and the FDA’s streamlined digital health guidelines exemplify proactive regulatory environments encouraging innovation. Moreover, North America’s emphasis on integrating digital health with traditional care models and its resilient economy position it attractively for sustained growth, offering significant opportunities for investors and strategists seeking to leverage evolving consumer and technological trends.
The United States anchors the North American mhealth solutions market with progressive digital health policies and substantial governmental support accelerating adoption. The U.S. Department of Health and Human Services has championed numerous programs to expand telehealth services, boosting consumer engagement in mobile health technologies. Additionally, the FDA’s approval of various mhealth apps as medical devices underscores regulatory clarity that reduces market entry barriers. Corporate developments, such as Apple’s integration of health monitoring features in its devices, reinforce the U.S. role as an innovation hub. These dynamics solidify the country’s position as a critical driver of regional growth, reinforcing North America’s dominance in the global mhealth solutions market.
Asia Pacific Market Analysis:
Asia Pacific emerged as the fastest-growing region in the mhealth solutions market, registering rapid growth with a robust CAGR of 15.6%. This significant expansion is driven primarily by the increasing need for effective management of chronic diseases alongside the challenge of limited access to conventional healthcare services in remote and rural areas. Governments and healthcare providers across the region have accelerated digital health initiatives to bridge these gaps, fostering adoption of mobile health platforms that enhance patient monitoring and remote care delivery. For instance, the Asia-Pacific Economic Cooperation (APEC) has advocated for digital health integration to improve rural healthcare outcomes. Additionally, rising smartphone penetration and digital literacy further empower patients to engage in self-management and teleconsultations, while regulatory agencies like the Japan Pharmaceuticals and Medical Devices Agency are streamlining approval processes for digital therapeutics. These dynamics collectively position Asia Pacific as a critical hub offering substantial opportunities for innovation and investment in the mhealth solutions market’s future.
Japan plays a pivotal role in the Asia Pacific mhealth solutions market due to its advanced aging population and high prevalence of chronic conditions, fueling demand for continuous remote health management. The country’s well-established digital infrastructure and supportive regulatory policies, exemplified by the Ministry of Health, Labour and Welfare’s initiatives on digital health tools, encourage widespread deployment of mhealth applications to mitigate healthcare system burdens. Japanese firms such as NTT Docomo are pioneering AI-driven telemedicine services that cater particularly to elderly patients, enhancing adherence to treatment plans and reducing hospital visits. This focus on tailored chronic disease management aligns with broader regional trends and underscores Japan’s leadership in shaping sustainable healthcare delivery models within Asia Pacific’s fast-growing mhealth market.
China’s expansive rural population and uneven healthcare access underscore its critical contribution to Asia Pacific’s mhealth market growth. The Chinese government’s investment in the Healthy China 2030 plan champions digital health solutions to overcome geographical disparities, boosting adoption of remote monitoring and mobile consultations in underserved areas. Corporations like Ping An Good Doctor leverage big data analytics and AI to deliver personalized care, improving outcomes for chronic disease patients in both urban and rural settings. Furthermore, increasing consumer adoption of mobile payment and health platforms supports seamless integration of mhealth services into daily life. This convergence of policy support, technology innovation, and consumer readiness in China bolsters the region’s overall momentum, reinforcing Asia Pacific’s status as a globally strategic market for mhealth solutions.
Europe Market Trends:
Europe maintained a substantial share in the mhealth solutions market, underscoring its leading role driven by an aging population and widespread digital health infrastructure. The region’s healthcare systems are increasingly integrating mobile health technologies to enhance patient monitoring and chronic disease management, responding to shifting consumer preferences toward remote care solutions. Supportive policy initiatives from the European Commission, such as the Digital Health and Care Strategy, have fostered regulatory harmonization enhancing cross-border interoperability. Major players benefit from well-established supply chains and advanced technological ecosystems, with competitive intensity encouraging ongoing innovation. For instance, the European Institute of Innovation & Technology highlighted collaborative projects accelerating wearable health device adoption. Going forward, Europe's mature yet evolving digital health landscape is poised to offer significant opportunities, particularly as sustainability and personalized medicine converge with mobile health technologies.
Germany serves as a pivotal market within Europe’s mhealth solutions market, driven by a robust healthcare system that rapidly embraces digital innovation amidst significant public health digitization efforts. The German Digital Healthcare Act, supporting reimbursement of mhealth apps, has stimulated both provider and consumer adoption, targeting chronic conditions prevalent in its demographic profile. Companies like Ada Health, a Berlin-based startup, exemplify how local innovation ecosystems catalyze cutting-edge mobile diagnostics tools. Germany’s emphasis on data privacy and cybersecurity, aligned with stringent regulations from the Federal Institute for Drugs and Medical Devices, ensures user trust, supporting sustained demand growth. Strategically, Germany’s leadership in regulatory progress and technology adoption reinforces its role as a gateway for broader European mhealth market penetration.
France plays an instrumental role in Europe's mhealth solutions market, with a unique blend of government-backed digital health initiatives and strong patient engagement fueling moderate growth. The French government’s Health Data Hub facilitates data access to innovators, supporting startups and established companies in developing AI-powered mobile health applications. Regulatory bodies like the National Agency for the Safety of Medicines and Health Products provide clear frameworks that encourage safe mhealth deployment alongside evolving reimbursement pathways. Firms such as Withings have capitalized on France’s culture of health-conscious consumers, advancing connected wellness devices. As France balances stringent healthcare standards with digital transformation momentum, it remains a critical market for scaling integrated mhealth solutions, enhancing regional market depth and competitive diversity.
| Parameter | North America | Asia Pacific | Europe | Latin America | MEA |
|---|---|---|---|---|---|
| Innovation HubiScaleNascentDeveloping Advanced | |||||
| Cost-Sensitive RegioniScaleLowMedium High | |||||
| Regulatory EnvironmentiScaleRestrictiveNeutral Supportive | |||||
| Demand DriversiScaleWeakModerate Strong | |||||
| Development StageiScaleEmergingDeveloping Developed | |||||
| Adoption RateiScaleLowMedium High | |||||
| New Entrants / StartupsiScaleSparseModerate Dense | |||||
| Macro IndicatorsiScaleWeakStable Strong |
mHealth Solutions Market Share (%), by Services And Products, 2026
Go beyond the chart, access full insights & data tables
Request Free Sample ReportThe mhealth solutions market in 2025 is dominated by the mHealth Apps segment, which represents the largest share among services and products. This leadership stems from widespread adoption of these apps for remote monitoring and wellness management, addressing growing consumer demand for personalized, real-time health insights. Enhanced smartphone penetration and digital literacy across diverse demographics have accelerated this trend, supported by streamlined regulatory pathways for health app approvals, as seen in the US FDA’s Digital Health Innovation Action Plan. Key players like Apple and Fitbit continue to innovate with advanced integration of biometric tracking and AI-driven recommendations, fostering strong competitive positioning. The segment’s ability to deliver scalable, user-friendly solutions also opens strategic opportunities for emerging firms to target niche conditions or regional markets. Given ongoing advancements in mobile technology and increasing healthcare digitization, mHealth apps are poised to remain pivotal in patient engagement and preventive care strategies.
| Segment | Sub-Segment | Largest Segment | Fastest Growing |
|---|---|---|---|
| Services And Products | Connected Medical Devices, mHealth Apps, mHealth Services |
Competitive Landscape and Market Positioning
The competitive landscape is marked by dynamic collaborations and iterative advancements, where top firms continuously enhance their offerings. Cross-sector alliances between device makers and software developers expand holistic care models. Apple and Fitbit have introduced new functionalities enhancing disease monitoring, while Qualcomm invests in connectivity enhancing telehealth scalability. Medtronic’s integration with mobile platforms elevates chronic disease management, and Philips enhances cloud-based diagnostic tools. Samsung and Huawei’s strategic expansions into AI-driven health analytics exemplify commitment to next-gen innovation. These initiatives collectively strengthen market positions, deepen user engagement, and widen competitive moats, driving persistent differentiation across multiple fronts.
Strategic / Actionable Recommendations for Regional Players
In North America, firms should deepen collaboration with technology leaders to co-develop advanced AI and machine learning applications, enhancing personalized health insights and improving clinical decision support, thereby reinforcing their leadership in innovation-intensive segments.
Asia Pacific players stand to benefit by forming alliances that emphasize scalability and affordability, combining cutting-edge digital health tools with localized distribution networks to capture rapidly growing consumer health awareness and address diverse regional needs efficiently.
European companies can capitalize on accumulating clinical data by investing in secure, interoperable platforms prioritizing regulatory compliance and data privacy, facilitating seamless integration with existing healthcare infrastructure to advance patient-centered care delivery and foster trust among users.
| Company | Market Share | Company Revenue | Revenue CAGR (%) | Product Portfolio | Geographic Presence | Innovation / R&D Focus | Strategic Developments |
|---|---|---|---|---|---|---|---|
| No companies available. | |||||||
Customize Your Report
Explore examples of how this report can be tailored to different research needs, including custom segments, additional topics or chapters, and related reports. Click a section of the wheel or its numbered marker to explore the available options.
mHealth Solutions Market — Custom Segments
| Segment | Sub-Segment |
|---|---|
| No segment data available. | |
mHealth Solutions Market — Custom TOC
| Custom Chapter | Chapter Details |
|---|---|
| No custom TOC data available. | |
Need a different cut of the data?
Request Custom ResearchFrequently Asked Questions
How will the mhealth solutions industry grow in terms of size and CAGR by 2035?
What is the leading region in terms of mhealth solutions market share?
Where has the mhealth solutions sector recorded the sharpest year-over-year increase?
Why does mhealth apps sub-segment dominate the services and products segment of mhealth solutions sector?
Which organizations are considered leaders in the mhealth solutions landscape?
Our Clients
"The team took the time to understand our specific business needs and delivered a report that was well aligned with our objectives. Their expertise and understanding of the industry were clearly reflected in the quality and relevance of the insights provided."
Siemens Healthcare
"Our experience in acquiring the research report has been excellent. The depth of analysis, and actionable insights provided have been extremely valuable in supporting our ongoing R&D efforts."
GC Biopharma
"The report offered a comprehensive view of the market trends. The in-depth segmentation and analysis of emerging opportunities gave us a better understanding of the market."
Medtronic
Our Research Team & Methodology
Every Fundamental Business Insights report is built by a dedicated vertical research team, validated through a structured primary-and-secondary methodology, and reviewed for accuracy before it reaches you.
Delivery
Published
Available
Support
- Market Size & Forecast
- Market Segmentation
- Regional Analysis
- Growth Drivers & Challenges
- Market Dynamics
- Competitive Landscape
- Company Profiles
- Competitive Benchmarking
- Mergers & Acquisitions
- Market Share Analysis or Key Company Strategies
- Value Chain Analysis
- Porter's Five Forces
- PESTLE Analysis
- Pricing Trends
- Supply-Demand Analysis
- Technology Landscape
- Regulatory Landscape
- Investment & Funding Landscape
- Emerging Opportunities
- Future Market Outlook