Caps and Closures Market Size & Growth Forecast 2027–2036, By Segments (Material, Product, Application), Regional Demand Trends (North America, Asia Pacific, Europe), Key Country Insights (U.S., Japan, South Korea, Germany, France, Italy), and Competitive Landscape
Jump to Content
Market Size and Growth Outlook
Caps and Closures Market size was around USD 116.6 billion in 2026 and is slated to grow at a 5.04% CAGR from 2027 to 2036, crossing USD 190.65 billion by 2036. The industry revenue for 2027 is assessed at USD 121.54 billion.
Get more details on this report
Request Free Sample ReportCaps and Closures Market Intelligence Snapshot
Regional Market Dynamics
- Asia Pacific held a 44.20% share in 2026, driven by high packaging demand across food, beverage, personal care, and household products, supported by a strong manufacturing base.
- North America is projected to expand at a 5.76% CAGR as demand rises for premium, functional, and compliance-focused packaging solutions that improve convenience, product integrity, and performance.
Segment Momentum
- Plastic is the largest and fastest-growing material because it supports lightweight, cost-effective, and high-volume production while offering design flexibility and compatibility across beverage, food, personal care, and household packaging.
- Dispensing caps are growing fastest because they improve convenience, controlled dispensing, and user experience, making them increasingly attractive for personal care, household, and selected food packaging applications.
Market Expansion Drivers
- Expanding food and beverage consumption increasing demand for secure and convenient packaging solutions.
- Growing dietary supplement usage driving adoption of dispensing and airtight closure systems.
- Rising urbanization and on-the-go consumption trends strengthening demand for portable packaging formats.
Leading Market Participants
- Prominent players in the caps and closures market include Amcor plc (Berry Global Group, Inc.) (Switzerland), Silgan Holdings Inc. (United States), AptarGroup, Inc. (United States), Crown Holdings, Inc. (United States), Closure Systems International, Inc. (United States), BERICAP Holding GmbH (Germany), Guala Closures S.p.A. (Italy), United Caps Luxembourg S.A. (Luxembourg), Ball Corporation (United States).
Global Market Forecast Snapshot
Market Outlook
- 2026 Market Size: USD 116.6 billion
- 2027 Estimated Market Size: USD 121.54 billion.
- Projected Market Size: USD 190.65 billion by 2036
- Growth Forecast: 5.04% CAGR (2027-2036)
Regional and Segment Outlook
- Leading Regional Market: Asia Pacific
- High-Growth Regional Hub: North America
- Core Revenue Segment: Plastic (Material) | Screw Closures (Product) | Beverages (Application)
- Emerging Opportunity Segment: Plastic (Material) | Dispensing Caps (Product) | Personal Care (Application)
Market Growth Drivers and Industry Trends
Expanding food and beverage consumption increasing demand for secure and convenient packaging solutions
Expanding consumption of packaged food and beverages will drive the caps and closures market growth by increasing requirements for packaging that combines product protection with ease of use. Food and beverage containers need secure closures to minimize leakage, preserve product integrity, and withstand handling during transportation and storage. Demand for resealable and user-friendly designs is also increasing as consumers seek packaging that supports convenient opening, closing, and repeated use across a broad range of packaged products.
Growing dietary supplement usage driving adoption of dispensing and airtight closure systems
Growing dietary supplement consumption is strengthening the caps and closures market as manufacturers require closure systems suited to products that need secure storage and convenient dispensing. Airtight designs can help limit exposure to moisture and air, supporting the protection of packaged supplements during storage and repeated use. Dispensing-oriented closures also improve handling by enabling controlled access to tablets, capsules, powders, and other supplement formats while maintaining a secure seal between uses.
Rising urbanization and on-the-go consumption trends strengthening demand for portable packaging formats
Rising urbanization and changing consumption habits are boosting the caps and closures market through increased demand for portable packaging that can be conveniently carried and consumed outside the home. On-the-go products require closures that provide reliable sealing, minimize spills, and allow consumers to open and reseal containers with limited effort. These functional requirements are encouraging greater adoption of practical closure formats across beverages, packaged foods, and other products designed for mobile consumption.
| Growth Driver | Impact on CAGR | Regulatory Influence | Geographic Relevance | Adoption Rate | Impact Timeline |
|---|---|---|---|---|---|
| Expanding food and beverage consumption increasing demand for secure and convenient packaging solutions | 1.80% | Moderate | Asia Pacific, North America | High | Near Term |
| Growing dietary supplement usage driving adoption of dispensing and airtight closure systems | 1.50% | Moderate | North America, Europe | High | Mid Term |
| Rising urbanization and on-the-go consumption trends strengthening demand for portable packaging formats | 1.40% | Low | Asia Pacific, Latin America | Medium | Mid Term |
Explore Growth Opportunities
Request Free Sample ReportRegional Demand Dynamics
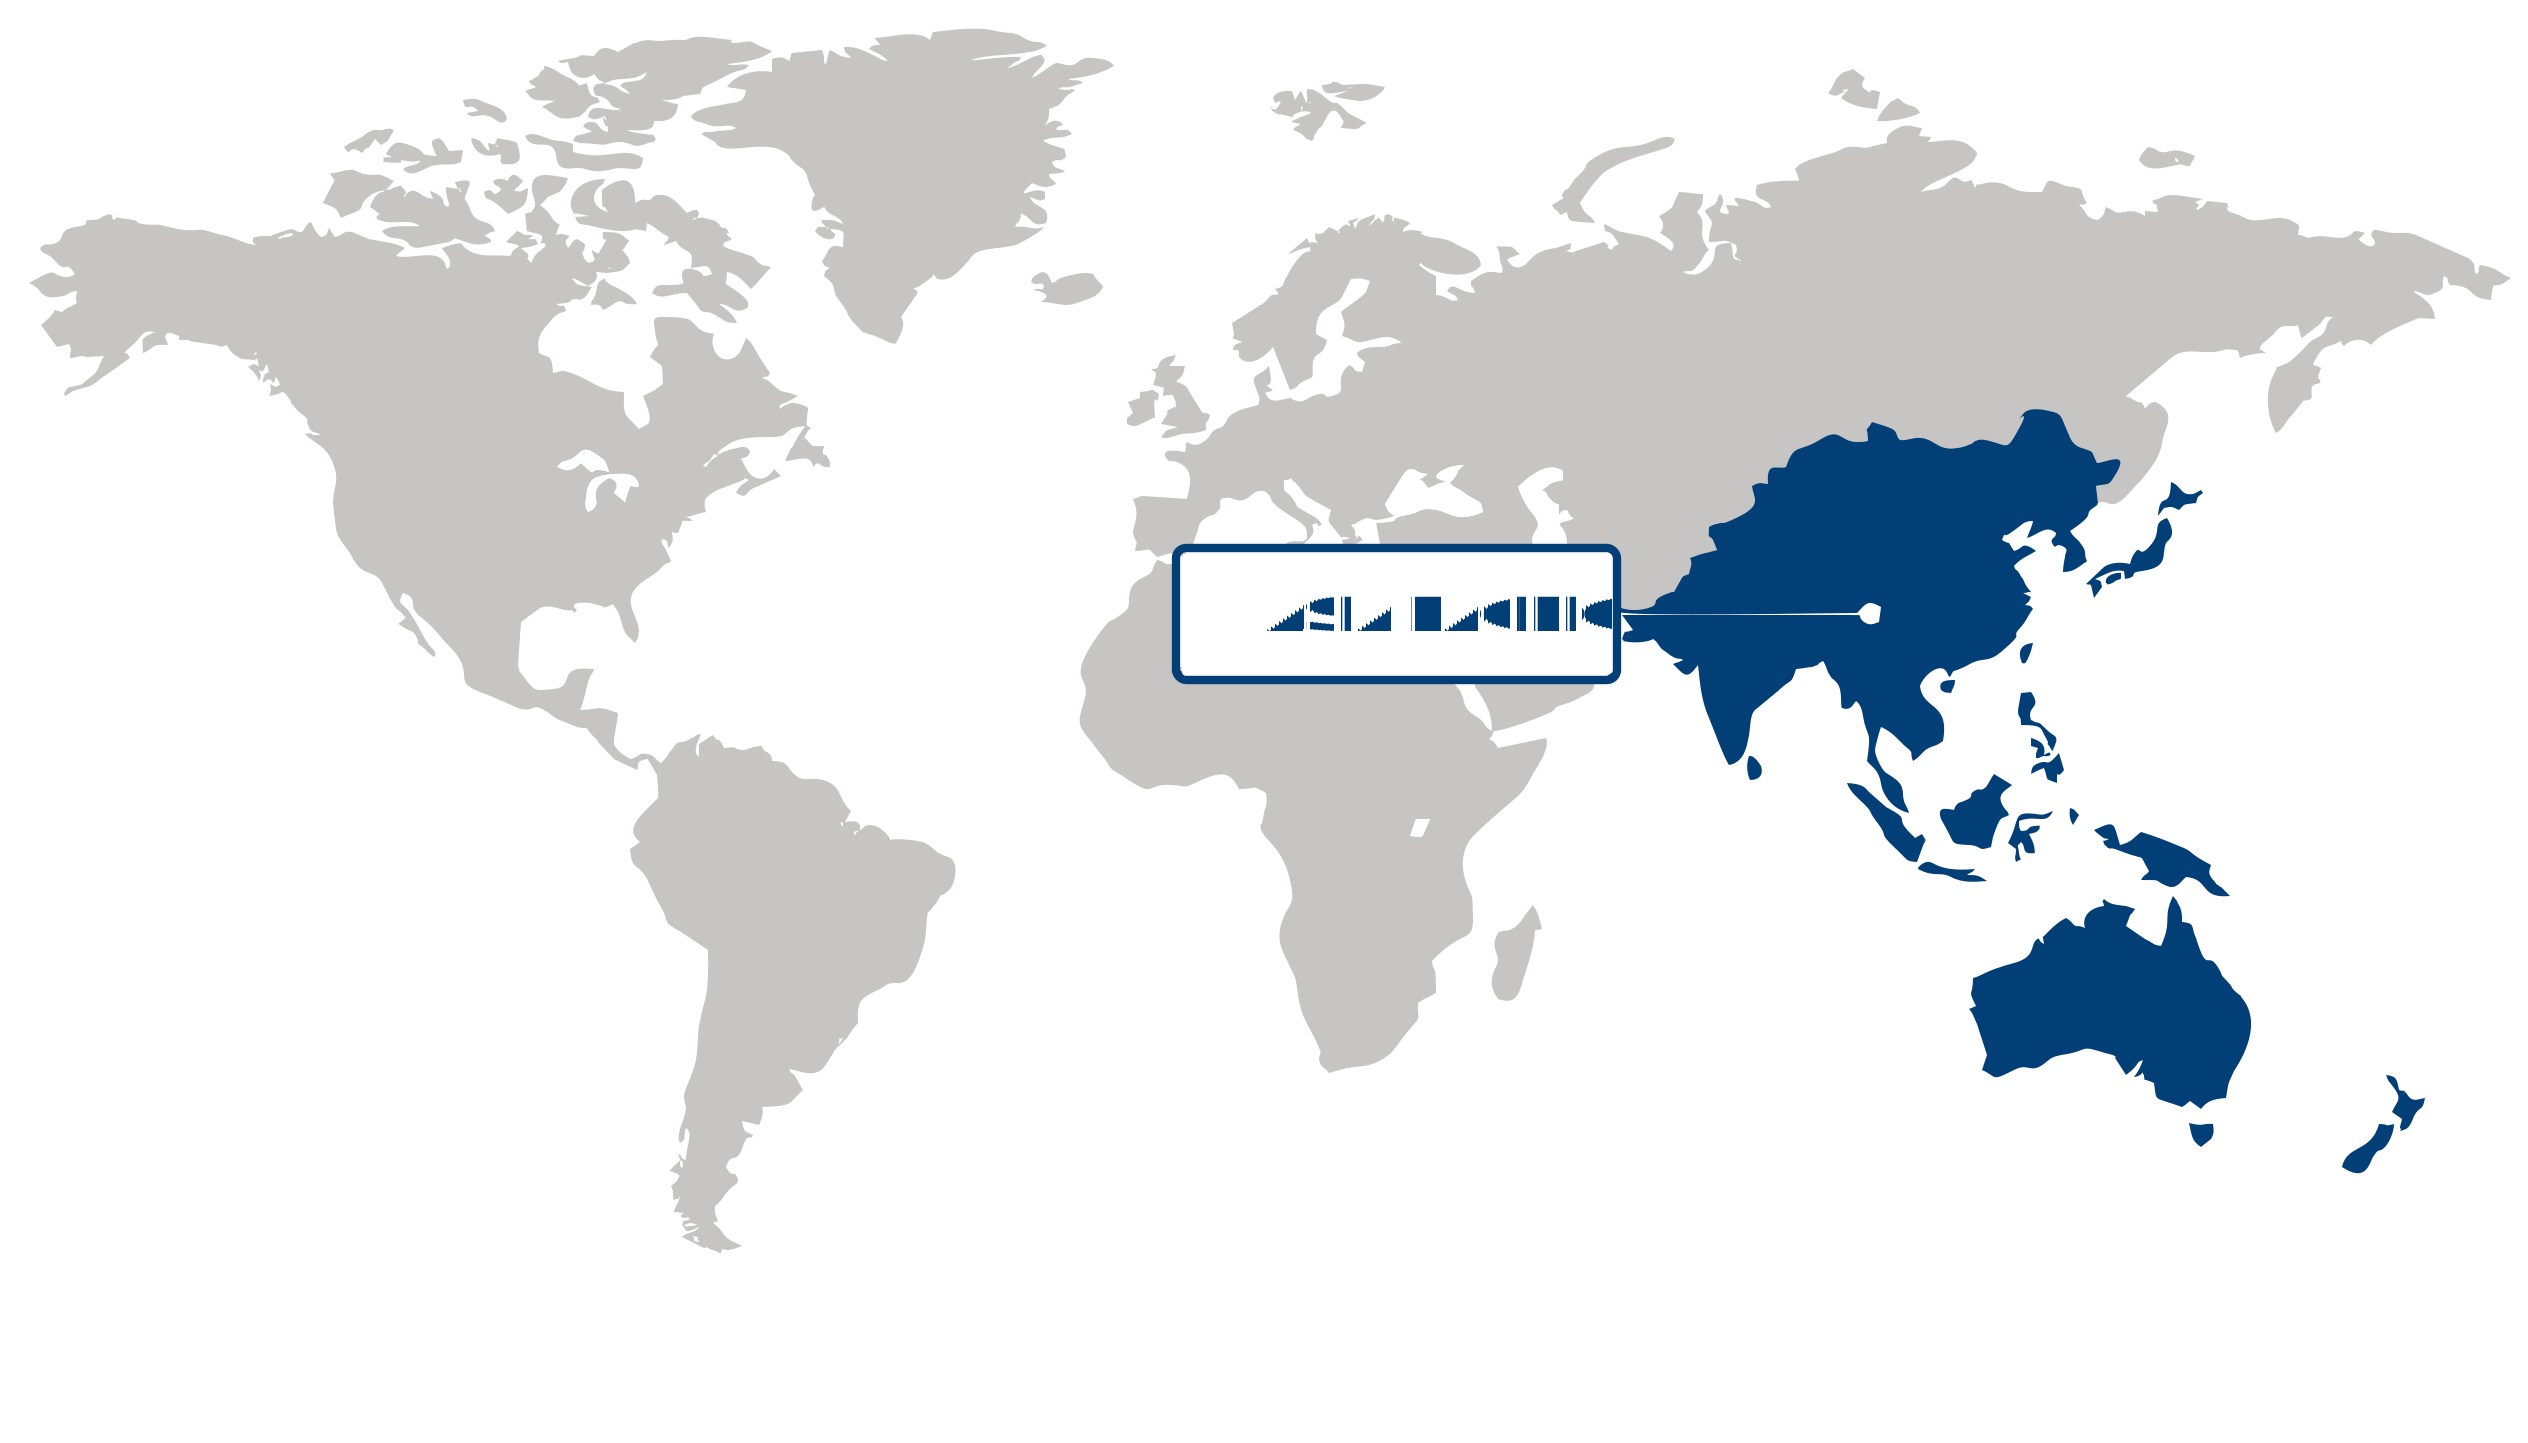
Asia Pacific (Largest Region)
Asia Pacific held the largest share of the caps and closures market at 44.20% in 2026, driven by substantial packaging demand from the food and beverage, pharmaceutical, personal care, and household product industries. Rapid urbanization, expanding consumer markets, and the increasing use of packaged products are supporting demand for functional and reliable closure solutions. Manufacturers are also responding to evolving consumer expectations around convenience, product safety, resealability, and packaging performance, encouraging continued development of innovative cap and closure formats. The region’s broad manufacturing base and expanding packaging industry further strengthen its position, while growing attention to material efficiency and sustainable packaging is influencing product development across multiple end-use sectors.
North America (Fastest-Growing Region)
North America represents the fastest-growing region, supported by continued innovation in packaging formats and rising demand for convenient, secure, and more sustainable closure solutions. Beverage, food, healthcare, and personal care producers are increasingly focused on packaging functionality, product protection, and consumer convenience, creating opportunities for advanced caps and closures. Sustainability considerations are also influencing material selection and packaging design, encouraging greater interest in recyclable and resource-efficient solutions. At the same time, established packaging infrastructure and ongoing investments in production technologies are enabling manufacturers to respond to changing regulatory expectations and end-user preferences, contributing to the region’s accelerated market development.
| Parameter | North America | Asia Pacific | Europe | Latin America | MEA |
|---|---|---|---|---|---|
| Innovation HubiScaleNascentDeveloping Advanced | |||||
| Cost-Sensitive RegioniScaleLowMedium High | |||||
| Regulatory EnvironmentiScaleRestrictiveNeutral Supportive | |||||
| Demand DriversiScaleWeakModerate Strong | |||||
| Development StageiScaleEmergingDeveloping Developed | |||||
| Adoption RateiScaleLowMedium High | |||||
| New Entrants / StartupsiScaleSparseModerate Dense | |||||
| Macro IndicatorsiScaleWeakStable Strong |
Key Country Insights
Germany 🇩🇪
Precision Manufacturing StandardsGermany focuses on precision-engineered caps and closures that support high-speed production and stringent quality requirements. Manufacturers in Germany continue investing in recyclable materials and advanced molding technologies to meet evolving packaging and environmental expectations.
France 🇫🇷
Sustainable Packaging IntegrationFrance advances the adoption of recyclable and eco-conscious caps and closures aligned with circular packaging initiatives. Producers in France work closely with food, beverage, and cosmetics companies to balance sustainability objectives with premium packaging performance.
Italy 🇮🇹
Design-Oriented ProductionItaly combines packaging aesthetics with manufacturing flexibility in the caps and closures market. Italian suppliers increasingly develop customized closure solutions for premium food, beverage, and luxury consumer goods while integrating recyclable materials into production.
Japan 🇯🇵
Functional Packaging DesignJapan prioritizes compact, user-friendly closure designs that enhance product usability while maintaining product integrity. The caps and closures market in Japan benefits from continuous refinement of dispensing systems and premium packaging formats for consumer and healthcare products.
South Korea 🇰🇷
Premium Consumer PackagingSouth Korea emphasizes visually appealing and functional caps and closures for cosmetics, beverages, and personal care products. Companies in South Korea increasingly adopt innovative materials and customized closure formats to strengthen product differentiation and consumer convenience.
United States 🇺🇸
Packaging Innovation FocusThe U.S. caps and closures market emphasizes lightweight packaging, tamper-evident solutions, and compatibility with automated filling lines. Brand owners in the U.S. increasingly prioritize sustainable material choices and closure designs that improve product convenience across food, beverage, and personal care applications.
Caps and Closures Market Share (%), by Material, 2026
Go beyond the chart, access full insights & data tables
Request Free Sample ReportMaterial Segment Analysis: Plastic (Largest & Fastest-Growing Segment)
The plastic segment led the caps and closures market in 2026 and is also expected to be the fastest-growing material category. Its strong position is supported by the lightweight nature, versatility, durability, and processing flexibility of plastic materials. Plastic caps and closures are widely used across beverages, food products, pharmaceuticals, personal care, and household goods because they can be manufactured in diverse shapes and designs while providing reliable sealing and convenient handling. Ongoing demand for lightweight packaging and improvements in recyclable and resource-efficient plastic solutions are further supporting adoption. The ability to incorporate tamper-evident features, dispensing mechanisms, and user-friendly designs also strengthens the material's relevance across packaging applications.
Product Segment Analysis: Screw Closures (Largest Segment) vs Dispensing Caps (Fastest-Growing Segment)
Screw closures represented the largest product segment of the caps and closures market in 2026, reflecting their broad use across consumer packaging applications. Their simple opening and closing mechanism, reliable sealing performance, and compatibility with a wide range of containers make them particularly suitable for beverages, food products, personal care items, and household products. Reclosability is another important advantage, allowing consumers to preserve product quality after initial opening. Continued demand for convenient and secure packaging formats is therefore reinforcing the widespread use of screw closures.
Dispensing caps are expected to be the fastest-growing product segment, supported by increasing consumer preference for packaging that combines convenience with controlled product delivery. These closures are particularly useful for products such as sauces, personal care formulations, household liquids, and other applications where precise dispensing can reduce spills and improve usability. Packaging manufacturers are increasingly incorporating user-oriented functionality into closure designs, including controlled-flow mechanisms and easy-open features. The growing emphasis on convenience, portion control, and enhanced consumer experience is expected to accelerate adoption of dispensing caps.
| Segment | Sub-Segment | Largest Segment | Fastest Growing |
|---|---|---|---|
| Material | Plastic, Metal, Others | Plastic | Plastic |
| Product | Dispensing Caps, Screw Closures, Crown Closures, Aerosol Closures, Others | Screw Closures | Dispensing Caps |
| Application | Beverages, Food, Healthcare, Personal Care, Home Care, Industrial | Beverages | Personal Care |
Unlock insights tailored to your business with our bespoke market research solutions.
Click to get your customized report now.
Competitive Landscape and Market Positioning
Leading companies in the caps and closures market:
1. Amcor plc (Berry Global Group Inc.) (Switzerland)
2. Silgan Holdings Inc. (United States)
3. AptarGroup Inc. (United States)
4. Crown Holdings Inc. (United States)
5. Closure Systems International Inc. (United States)
6. BERICAP Holding GmbH (Germany)
7. Guala Closures S.p.A. (Italy)
8. United Caps Luxembourg S.A. (Luxembourg)
9. Ball Corporation (United States)
The caps and closures market is evolving with innovations focused on improved sealing performance and packaging sustainability. New product designs are addressing changing consumer packaging preferences across food and beverage applications. Continuous R&D is enhancing material strength and recyclability, while evolving demand trends are driving functional and eco-friendly packaging solutions.
| Company | Market Share | Company Revenue | Revenue CAGR (%) | Product Portfolio | Geographic Presence | Innovation / R&D Focus | Strategic Developments |
|---|---|---|---|---|---|---|---|
| Amcor plc (Berry Global Group Inc.) (Switzerland) | |||||||
| Silgan Holdings Inc. (United States) | |||||||
| AptarGroup Inc. (United States) | |||||||
| Crown Holdings Inc. (United States) | |||||||
| Closure Systems International Inc. (United States) | |||||||
| BERICAP Holding GmbH (Germany) | |||||||
| Guala Closures S.p.A. (Italy) | |||||||
| United Caps Luxembourg S.A. (Luxembourg) | |||||||
| Ball Corporation (United States). |
Industry Development/News
| Company Name | Date | Key Development |
|---|---|---|
| BERICAP | May-26 | BERICAP acquired Ireland-based Embankment Plastics, a supplier of dairy, food, and technical closures. This acquisition expands the company’s global footprint, strengthens local manufacturing capabilities, and enhances its competitive position within key packaging end markets. |
| Indorama Ventures | Mar-26 | Indorama Ventures announced the merger of its rigid packaging operations with EPL Ltd.’s flexible packaging business. This integration creates a larger packaging platform intended to accelerate growth opportunities in emerging markets and strengthen the company’s consolidated packaging portfolio. |
| Corvaglia Group | Nov-25 | Corvaglia Group combined its Swiss manufacturing operations with the European production network of Wisecap Group. This transaction increases manufacturing scale and enhances the combined entity’s presence and operational footprint in the European plastic caps and closures market. |
| Origin Materials | Aug-25 | Origin Materials achieved the first commercial deployment of its PET Cap technology through a launch with Power Hydration. The development enables fully recyclable PET bottle-and-cap systems, advancing monomaterial packaging solutions and supporting circularity in the beverage packaging segment. |
| SIG | Jul-25 | SIG partnered with PulPac to develop paper-based closures utilizing Dry Molded Fiber technology. This collaboration supports the development of renewable packaging alternatives, aligning with industry-wide efforts to increase fiber content and reduce reliance on fossil-based materials in closure applications. |
| PulPac | May-25 | SIG InnoVentures and Optima joined PulPac’s ownership group as strategic investors. This capital injection strengthens support for the commercialization and industrial scaling of Dry Molded Fiber technology, which is increasingly applied to sustainable closure solutions. |
| Ekam Global | Apr-25 | Ekam Global entered a strategic partnership with Blue Ocean Closures to commercially deploy a cellulose fiber screw cap. This initiative marks the first commercial use of this technology, highlighting significant industry momentum toward fiber-based and circular packaging alternatives to traditional plastic closures. |
| TriMas Packaging | Nov-24 | TriMas Packaging opened a 225,000-square-foot manufacturing facility in Haining, China. The site integrates injection molding, assembly, and clean-room capabilities, significantly expanding the company’s production capacity and regional presence for high-demand packaging and closure products. |
| Manjushree Technopack Ltd. (MTL) | Apr-24 | MTL acquired the plastics packaging business of Oriental Containers. This transaction is expected to double MTL’s market share in the caps and closures segment and substantially expand its manufacturing capacity, thereby strengthening its competitive positioning in the regional market. |
| Blue Ocean Closures | Apr-24 | Blue Ocean Closures commercially launched its fiber-based screw cap in partnership with Great Earth. Designed for paper waste streams, this recyclable closure represents a strategic alternative to conventional plastic formats, addressing market demand for plastic-free packaging solutions. |
Customize Your Report
Explore examples of how this report can be tailored to different research needs, including custom segments, additional topics or chapters, and related reports. Click a section of the wheel or its numbered marker to explore the available options.
Caps and Closures Market — Custom Segments
| Segment | Sub-Segment |
|---|---|
| Closure Mechanism | Screw-On, Snap-On, Crimp-On, Push-Pull, Flip-Top |
| Tamper-Evidence Type | Tamper-Evident Bands, Breakaway Rings, Tear Strips, Induction Seals, Other Integrated Features |
| Sustainability Profile | Recyclable Closures, Lightweight Closures, Recycled-Content Closures, Bio-Based Closures |
Caps and Closures Market — Custom TOC
| Custom Chapter | Chapter Details |
|---|---|
| Sustainable Packaging Transition Assessment |
|
| Brand Owner Packaging Preference Analysis |
|
| Closure Innovation and Differentiation Landscape |
|
Need a different cut of the data?
Request Custom ResearchFrequently Asked Questions
How much revenue does the caps and closures market generate?
What is the forecasted size of the caps and closures industry?
How is expanding food and beverage consumption driving demand in the caps and closures market?
Why is growing dietary supplement usage increasing demand for specialized closure systems?
Why is plastic the leading material in the caps and closures market?
Why are dispensing caps the fastest-growing product segment in the caps and closures market?
Why is Asia Pacific the largest caps and closures market?
What is fueling caps and closures market growth in North America?
What are the prominent companies operating in the caps and closures landscape?
Our Clients
"The report provided a thorough look at market trends, technological advancements, and the competitive landscape. The depth of insights was really valuable."
ITC Limited
"We would highly recommend Fundamental Business Insights & Consulting to anyone looking for reliable, detailed, and comprehensive market research in the Food industry."
Tyson Foods
"The clarity and presentation of the information were commendable. The report was delivered timely, which made the overall experience smooth and convenient."
Mondelēz International
Our Research Team & Methodology
Every Fundamental Business Insights report is built by a dedicated vertical research team, validated through a structured primary-and-secondary methodology, and reviewed for accuracy before it reaches you.
This report was prepared by the Food & Beverage Research Team at Fundamental Business Insights, a dedicated research group specializing in the global food, beverage, ingredients, and food processing industries. Our analysts continuously monitor evolving consumer preferences, product innovation, ingredient developments, food safety regulations, manufacturing technologies, supply chain dynamics, pricing trends, sustainability initiatives, and changing retail and foodservice landscapes to deliver timely and reliable market intelligence. The research is developed using a structured methodology that combines primary discussions with food manufacturers, ingredient suppliers, distributors, retailers, industry experts, and other key stakeholders, along with company annual reports, regulatory publications, government trade statistics, food safety authorities, industry associations, technical publications, and other authoritative secondary sources. Market estimates are validated through multiple research techniques, including top-down and bottom-up analysis, before undergoing an internal quality review to ensure accuracy, consistency, and methodological integrity prior to publication.
Delivery
Published
Available
Support
- Market Size & Forecast
- Market Segmentation
- Regional Analysis
- Growth Drivers & Challenges
- Market Dynamics
- Competitive Landscape
- Company Profiles
- Competitive Benchmarking
- Mergers & Acquisitions
- Market Share Analysis or Key Company Strategies
- Value Chain Analysis
- Porter's Five Forces
- PESTLE Analysis
- Pricing Trends
- Supply-Demand Analysis
- Technology Landscape
- Regulatory Landscape
- Investment & Funding Landscape
- Emerging Opportunities
- Future Market Outlook