Industrial Plastic Bags Market Size & Growth Forecast 2027–2036, By Segments (Bag Type, End Use Industry, Material), Regional Demand Trends (North America, Asia Pacific, Europe), Key Country Insights (U.S., Japan, South Korea, Germany, France, Italy), and Competitive Landscape
Jump to Content
Market Size and Growth Outlook
Industrial Plastic Bags Market size was worth USD 13.39 Billion in 2026 and is expected to grow at 6.15% CAGR between 2027 and 2036, crossing USD 24.32 Billion by 2036. The industry revenue for 2027 is assessed at USD 14.09 Billion.
Get more details on this report
Request Free Sample ReportIndustrial Plastic Bags Market Intelligence Snapshot
Regional Market Dynamics
- North America held 32.51% in 2026, supported by established manufacturing, logistics, food processing, retail, industrial distribution, and demand for durable packaging.
- Asia Pacific is projected to grow fastest as industrialization, manufacturing, retail, logistics networks, and investment in production infrastructure expand regional packaging demand.
Segment Momentum
- Polyethylene (PE) held the largest market position in 2026 because it combines flexibility, durability, moisture resistance, and cost efficiency, making it suitable for a wide range of industrial packaging applications.
- Agriculture is the fastest-growing end-use segment as producers increasingly require durable packaging for seeds, fertilizers, feed, and harvested crops to improve storage, transportation, and reduce product losses.
Market Expansion Drivers
- Growth in manufacturing and industrial sectors driving bulk packaging material demand
- Expanding e-commerce and retail sector increasing demand for flexible packaging solutions
- Rising infrastructure and construction activity boosting industrial material packaging requirements
Leading Market Participants
- Top players in the industrial plastic bags market include Amcor plc (Australia), Mondi Group plc (United Kingdom), Sealed Air Corporation (United States), Novolex Holdings, LLC (United States), Huhtamaki Oyj (Finland), Coveris Holdings S.A. (Luxembourg), Winpak Ltd. (Canada), Uflex Limited (India), Inteplast Group (United States), Poly-America, L.P. (United States)
Global Market Forecast Snapshot
Market Outlook
- 2026 Market Size: USD 13.39 Billion
- 2027 Estimated Market Size: USD 14.09 Billion
- Projected Market Size: USD 24.32 Billion by 2036
- Growth Forecast: 6.15% CAGR (2027-2036)
Regional and Segment Outlook
- Leading Regional Market: North America
- High-Growth Regional Hub: Asia Pacific
- Core Revenue Segment: Woven Sacks (Bag Type) | Manufacturing (End Use Industry) | Polyethylene (PE) (Material)
- Emerging Opportunity Segment: Woven Sacks (Bag Type) | Agriculture (End Use Industry) | Biodegradable Plastic (Material)
Market Growth Drivers and Industry Trends
Growth in manufacturing and industrial sectors driving bulk packaging material demand
Expanding industrial production is increasing the need for reliable packaging materials capable of protecting raw materials, intermediate goods, and finished products throughout storage and transportation. The industrial plastic bags market is supported by rising demand for bulk packaging solutions that offer durability, moisture resistance, and efficient handling across manufacturing environments. Industrial facilities increasingly rely on high-strength plastic bags to streamline material movement while protecting products from contamination and physical damage during logistics operations.
Expanding e-commerce and retail sector increasing demand for flexible packaging solutions
The continued growth of e-commerce and organized retail is driving greater consumption of flexible packaging products that support efficient order fulfillment and product distribution. The industrial plastic bags market benefits as packaging suppliers provide versatile bag formats suitable for warehousing, shipping, inventory management, and secondary packaging applications. Flexible plastic bags also improve handling efficiency while accommodating diverse product categories that require lightweight, durable, and cost-effective packaging throughout increasingly complex supply chains.
Rising infrastructure and construction activity boosting industrial material packaging requirements
Large-scale infrastructure development and construction projects require dependable packaging solutions for transporting and storing a wide range of building materials and industrial supplies. The industrial plastic bags market is expanding as contractors and material suppliers adopt heavy-duty plastic bags capable of protecting cement, aggregates, chemicals, insulation materials, and other construction inputs from environmental exposure during handling and distribution. Their strength, portability, and resistance to harsh site conditions make them well suited for demanding construction logistics and material management applications.
| Growth Driver | Impact on CAGR | Regulatory Influence | Geographic Relevance | Adoption Rate | Impact Timeline |
|---|---|---|---|---|---|
| Growth in manufacturing and industrial sectors driving bulk packaging material demand | 2% | Moderate | Asia Pacific, North America, Middle East & Africa | High | Near Term |
| Expanding e-commerce and retail sector increasing demand for flexible packaging solutions | 1.8% | Moderate | Asia Pacific, North America, Europe | High | Near Term |
| Rising infrastructure and construction activity boosting industrial material packaging requirements | 1.5% | Moderate | Asia Pacific, Middle East & Africa | Medium | Mid Term |
Unlock insights tailored to your business with our bespoke market research solutions.
Click to get your customized report now.
Regional Demand Dynamics
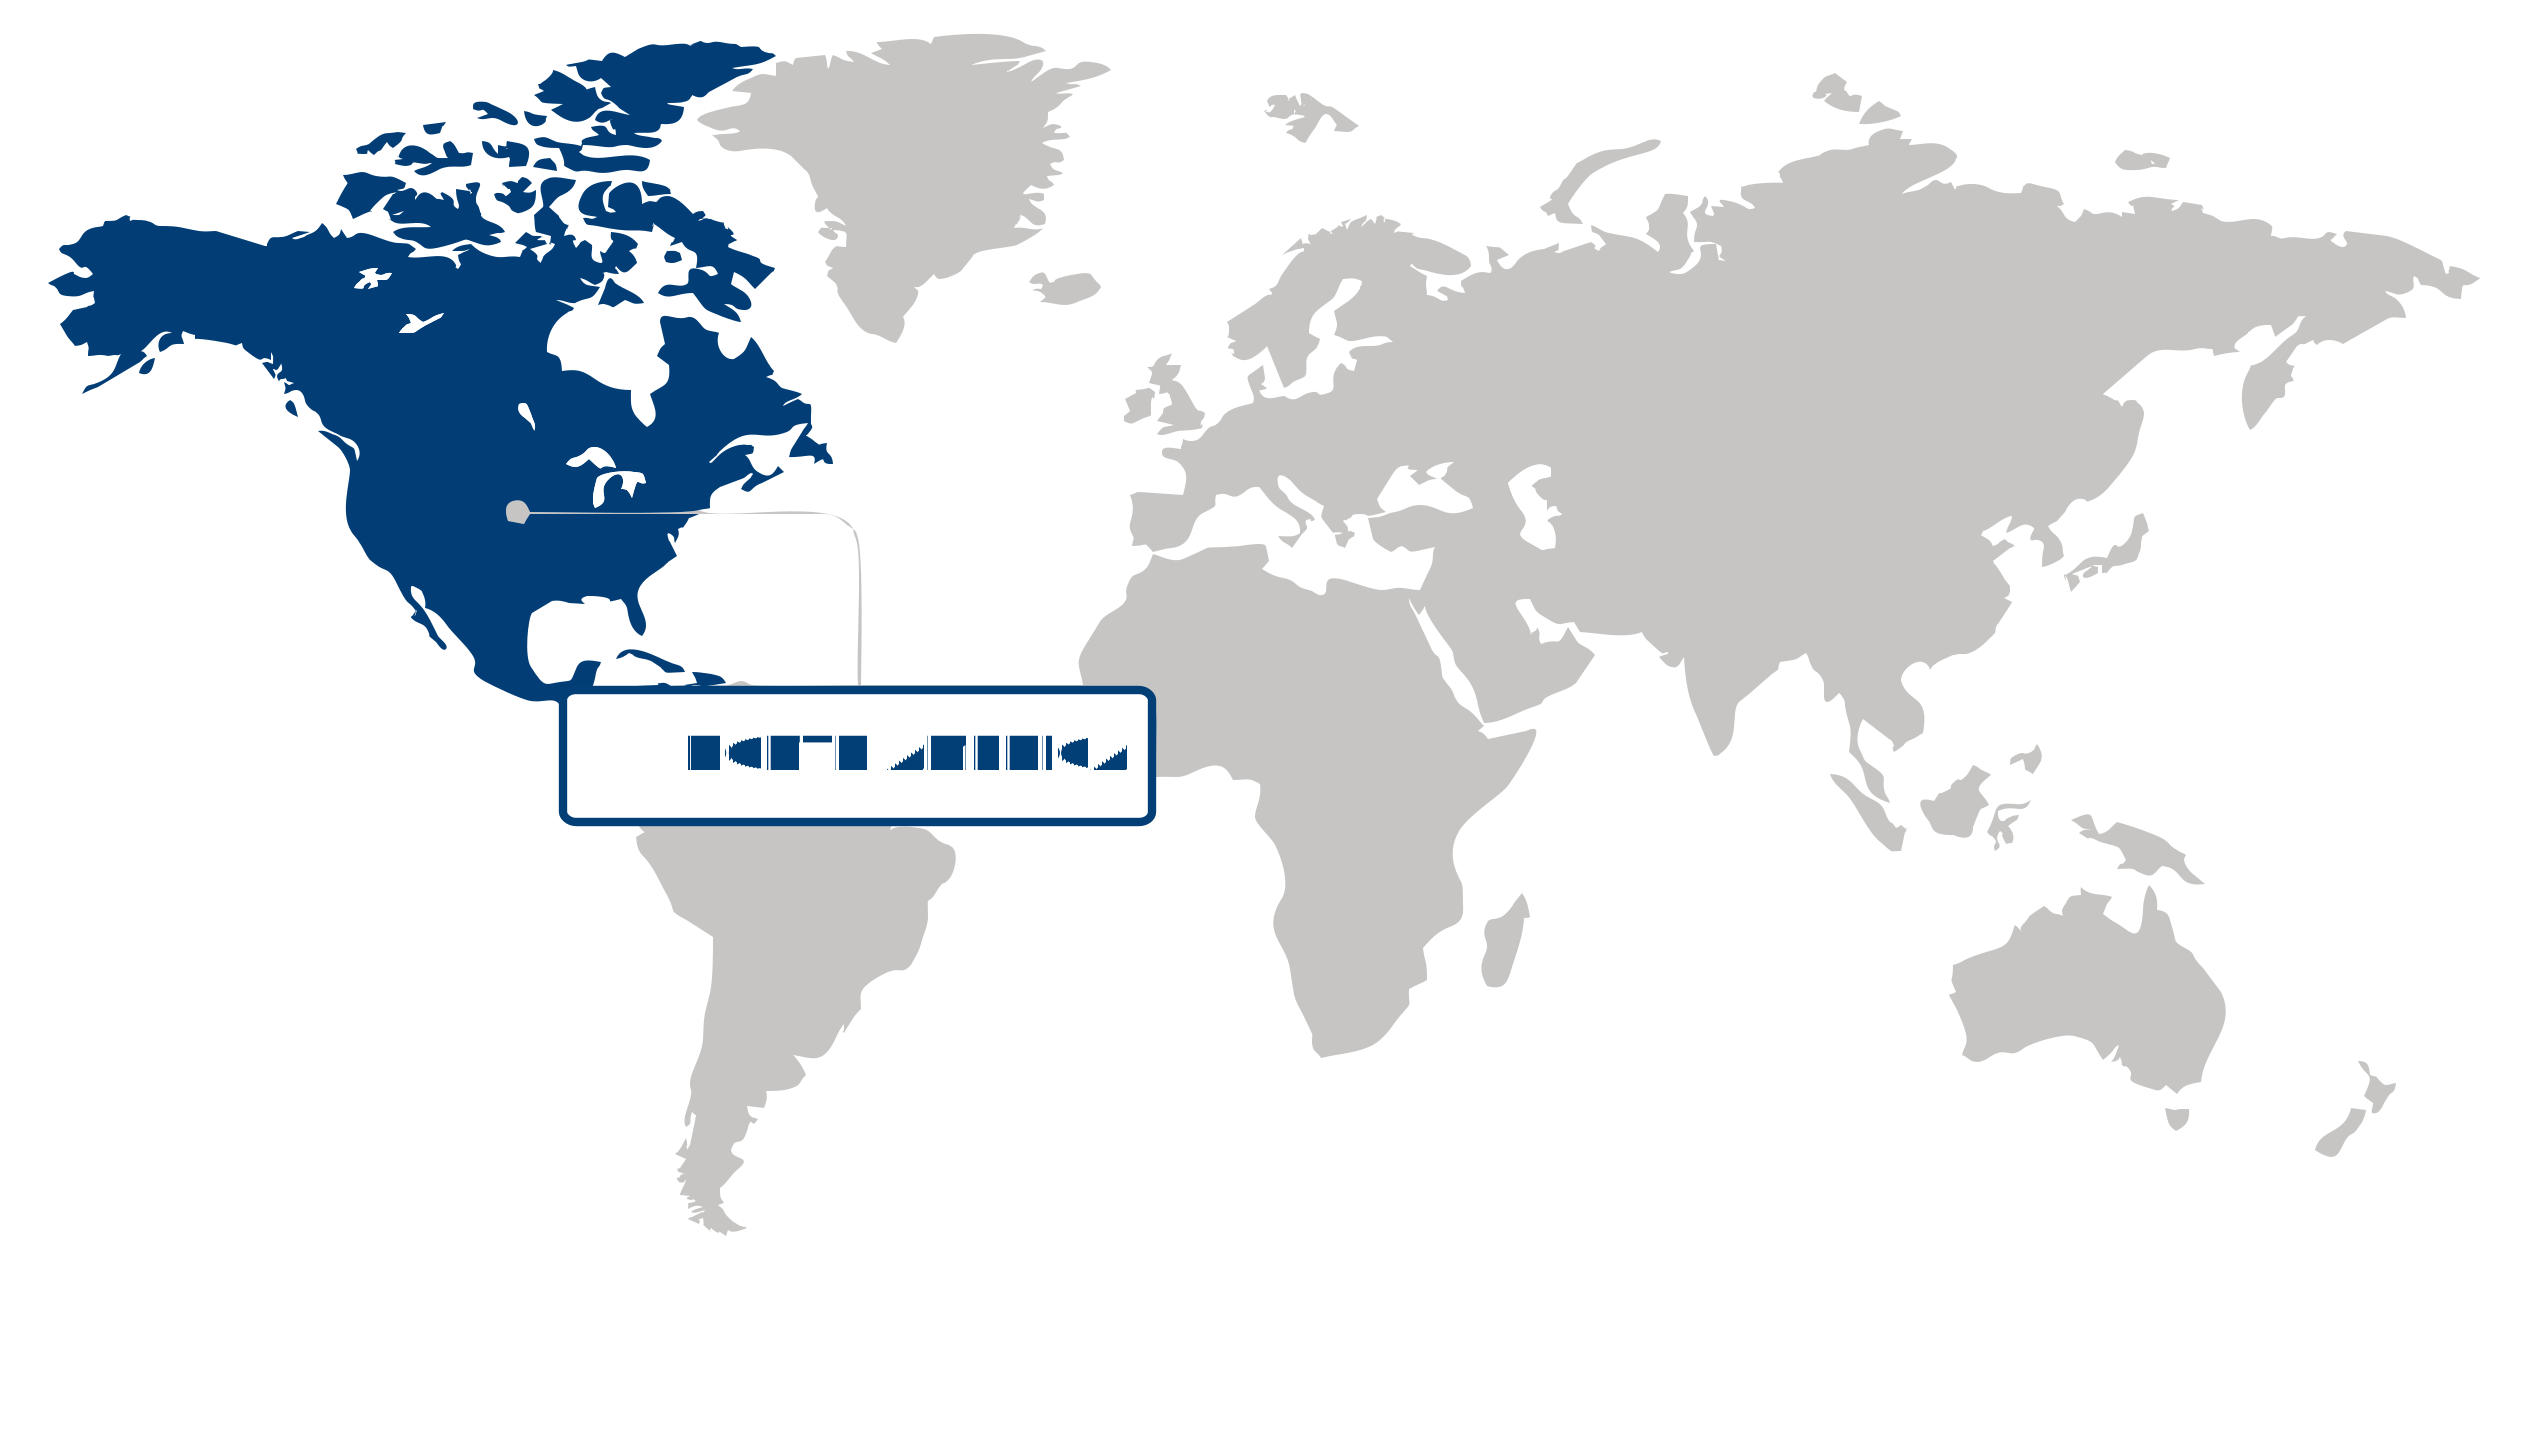
North America (Largest Region)
North America accounted for 32.51% of the industrial plastic bags market in 2026, supported by well-established manufacturing, logistics, food processing, retail, and industrial distribution activities. Demand for durable and cost-efficient packaging remains strong across applications requiring protection, transportation, storage, and handling of bulk materials. The region's developed supply chains and emphasis on packaging performance are supporting the use of specialized plastic bags for industrial applications. At the same time, increasing attention to waste reduction and material efficiency is encouraging manufacturers to develop recyclable and resource-efficient packaging formats, creating opportunities for product innovation.
Asia Pacific (Fastest-Growing Region)
Asia Pacific is expected to be the fastest-growing region, driven by rapid industrialization, expanding manufacturing activity, and the development of retail and logistics networks. Growing production of consumer goods, food products, chemicals, and other industrial materials is increasing the need for flexible packaging solutions that can support efficient handling and transportation. Urbanization and the expansion of organized distribution channels are further broadening the application base for industrial plastic bags. Rising investment in manufacturing infrastructure and growing interest in lightweight, durable, and recyclable packaging solutions are expected to strengthen regional demand.
| Parameter | North America | Asia Pacific | Europe | Latin America | MEA |
|---|---|---|---|---|---|
| Innovation HubiScaleNascentDeveloping Advanced | |||||
| Cost-Sensitive RegioniScaleLowMedium High | |||||
| Regulatory EnvironmentiScaleRestrictiveNeutral Supportive | |||||
| Demand DriversiScaleWeakModerate Strong | |||||
| Development StageiScaleEmergingDeveloping Developed | |||||
| Adoption RateiScaleLowMedium High | |||||
| New Entrants / StartupsiScaleSparseModerate Dense | |||||
| Macro IndicatorsiScaleWeakStable Strong |
Key Country Insights
United States 🇺🇸
Performance Packaging DemandThe U.S. industrial plastic bags market emphasizes durable packaging solutions for manufacturing, chemicals, agriculture, and distribution sectors. U.S. producers are expanding recyclable materials and high-strength bag formats while responding to customer expectations for operational efficiency and sustainability.
Germany 🇩🇪
Circular Packaging SolutionsGermany prioritizes industrial plastic bags that align with recycling objectives and stringent material standards. German manufacturers continue investing in recycled resin integration, lightweight designs, and high-performance packaging suitable for industrial logistics and export-oriented production.
Japan 🇯🇵
Precision Material PerformanceJapan focuses on industrial plastic bags offering consistent quality, material efficiency, and reliable protection for sensitive industrial products. Japanese suppliers continue refining advanced polymer formulations and production technologies that improve durability while reducing material consumption.
South Korea 🇰🇷
Export Packaging EfficiencySouth Korea supports industrial plastic bag production through advanced converting capabilities and export-driven manufacturing. South Korean suppliers emphasize customized packaging formats, improved barrier properties, and sustainable material options for industrial customers serving international markets.
France 🇫🇷
Sustainable Industrial PackagingFrance encourages industrial plastic bag solutions that balance performance with environmental compliance. French manufacturers increasingly incorporate recycled content and recyclable designs while supporting industrial sectors seeking practical packaging alternatives that meet evolving sustainability requirements.
Italy 🇮🇹
Flexible Manufacturing SupplyItaly emphasizes customized industrial plastic bags for food processing, manufacturing, construction, and specialty industries. Italian producers continue expanding flexible production capabilities that accommodate varying product specifications while maintaining packaging durability and cost efficiency.
Industrial Plastic Bags Market Share (%), by Bag Type, 2026
Go beyond the chart, access full insights & data tables
Request Free Sample ReportBag Type Segment Analysis: Woven Sacks (Largest & Fastest-Growing Segment)
the woven sacks segment dominated the industrial plastic bags market, accounting for 28.19% of the market share in 2026, while also representing the fastest-growing bag type. Woven sacks are widely utilized because they provide excellent strength, durability, and resistance to tearing, making them suitable for transporting and storing heavy industrial materials. Their extensive use across sectors such as agriculture, construction, chemicals, and manufacturing has reinforced their market leadership. Increasing demand for reliable bulk packaging solutions, along with continued improvements in material performance and handling efficiency, is expected to sustain the segment's strong growth trajectory.
End Use Industry Segment Analysis: Manufacturing (Largest Segment) vs Agriculture (Fastest-Growing Segment)
the manufacturing end-use industry held 27% of the market share in 2026, making it the largest segment in the industrial plastic bags market. Manufacturing operations require durable packaging solutions for handling raw materials, intermediate goods, and finished products across diverse production environments. Industrial plastic bags help improve storage efficiency, facilitate transportation, and protect products from contamination and damage during distribution. The continued expansion of industrial production and supply chain activities has strengthened demand from the manufacturing sector.
the agriculture end-use industry is the fastest-growing segment as agricultural producers increasingly require reliable packaging for seeds, fertilizers, animal feed, harvested crops, and other farm-related materials. Durable plastic bags improve storage conditions, simplify transportation, and reduce product losses throughout agricultural supply chains. Rising agricultural productivity and growing emphasis on efficient post-harvest handling are supporting the increasing adoption of industrial plastic bags within this sector.
Material Segment Analysis: Polyethylene (PE) (Largest Segment) vs Biodegradable Plastic (Fastest-Growing Segment)
the polyethylene (PE) segment held the largest position in the industrial plastic bags market in 2026. Polyethylene remains the preferred material because it offers an effective combination of flexibility, durability, moisture resistance, and cost efficiency across a broad range of industrial packaging applications. Its versatility allows manufacturers to produce bags suitable for heavy-duty handling as well as general industrial use, contributing to its widespread adoption across multiple end-use industries.
the biodegradable plastic segment is emerging as the fastest-growing material category due to increasing demand for environmentally responsible packaging solutions. Businesses are placing greater emphasis on reducing plastic waste and adopting materials that align with evolving sustainability objectives and regulatory expectations. Continued innovation in biodegradable materials and growing environmental awareness are accelerating the adoption of this segment across industrial packaging applications.
| Segment | Sub-Segment | Largest Segment | Fastest Growing |
|---|---|---|---|
| Bag Type | Flat Bags, Gusseted Bags, Trash Bags, Woven Sacks, Valve Bag, Others | Woven Sacks | Woven Sacks |
| End Use Industry | Construction, Agriculture, Chemical, Food & Beverage, Manufacturing, Others | Manufacturing | Agriculture |
| Material | Polyethylene (PE), Polypropylene (PP), Polyvinyl Chloride (PVC), Biodegradable Plastic, Recycled Plastic, Others | Polyethylene (PE) | Biodegradable Plastic |
Competitive Landscape and Market Positioning
Key companies in the industrial plastic bags market:
- Amcor plc (Australia)
- Mondi Group plc (United Kingdom)
- Sealed Air Corporation (United States)
- Novolex Holdings LLC (United States)
- Huhtamaki Oyj (Finland)
- Coveris Holdings S.A. (Luxembourg)
- Winpak Ltd. (Canada)
- Uflex Limited (India)
- Inteplast Group (United States)
- Poly-America L.P. (United States)
Competitive priorities in the industrial plastic bags market are shifting from high-volume production alone toward the ability to deliver application-specific performance while meeting evolving sustainability expectations. Manufacturers are investing in advanced material formulations, improved durability, and customized packaging designs that address the handling requirements of industries ranging from chemicals to construction and agriculture. Suppliers with flexible manufacturing capabilities, consistent product quality, and efficient raw material management are strengthening their position as buyers increasingly seek dependable packaging solutions that balance operational performance with environmental considerations.
| Company | Market Share | Company Revenue | Revenue CAGR (%) | Product Portfolio | Geographic Presence | Innovation / R&D Focus | Strategic Developments |
|---|---|---|---|---|---|---|---|
| Amcor plc (Australia) | |||||||
| Mondi Group plc (United Kingdom) | |||||||
| Sealed Air Corporation (United States) | |||||||
| Novolex Holdings LLC (United States) | |||||||
| Huhtamaki Oyj (Finland) | |||||||
| Coveris Holdings S.A. (Luxembourg) | |||||||
| Winpak Ltd. (Canada) | |||||||
| Uflex Limited (India) | |||||||
| Inteplast Group (United States) | |||||||
| Poly-America L.P. (United States) |
Industry Development/News
| Company Name | Date | Key Development |
|---|---|---|
| Yara | Nov-23 | Yara signed a contract with a Brazil-based supplier for the construction of a new agricultural bag made from 100 percent recycled polyethylene terephthalate to advance sustainable packaging goals and minimize environmental impact. |
| UltraTech Cement Limited | Jul-23 | UltraTech Cement developed new sustainable cement packaging solutions incorporating 50 percent recycled polypropylene materials, which reduce virgin plastic consumption by 43 percent per bag to support circular economy practices. |
| Knack Packaging | — | Knack Packaging enhanced its production capabilities by acquiring a bottom-gusset industrial bag-making machine, enabling higher output and shorter lead times for industrial woven polypropylene bags to meet rising market demand. |
Customize Your Report
Explore examples of how this report can be tailored to different research needs, including custom segments, additional topics or chapters, and related reports. Click a section of the wheel or its numbered marker to explore the available options.
Industrial Plastic Bags Market — Custom Segments
| Segment | Sub-Segment |
|---|---|
| Closure Type | Open-mouth, Drawstring, Zipper, Valve, Adhesive/Heat-sealed |
| Distribution Channel | Direct Sales, Distributors & Wholesalers, Retail & E-commerce |
| Reusability | Single-use Bags, Limited-reuse Bags, Reusable Bags |
Industrial Plastic Bags Market — Custom TOC
| Custom Chapter | Chapter Details |
|---|---|
| Industrial Packaging Procurement Intelligence |
|
| Material Substitution and Sustainability Pathways |
|
| Circularity and Take-Back Strategies |
|
Need a different cut of the data?
Request Custom ResearchFrequently Asked Questions
How much revenue does the industrial plastic bags market generate?
What are the growth projections for the industrial plastic bags industry?
How is industrial expansion influencing demand for industrial plastic bags?
Why is e-commerce growth supporting the industrial plastic bags market?
Why is polyethylene (PE) the leading material in the industrial plastic bags market?
Why is agriculture the fastest-growing end-use industry for industrial plastic bags?
What makes North America the largest industrial plastic bags market?
Why is Asia Pacific expected to grow fastest?
What are the prominent companies operating in the industrial plastic bags landscape?
Our Clients
"The report helped us understand emerging consumer trends in our product category. It clarified where to focus innovation for the next product launch."
LyondellBasell
"The regional forecast section was incredibly useful. We were able to identify two new potential partners in Europe thanks to the vendor mapping you included."
SABIC
"We appreciated how actionable the recommendations were. It guided us to improve supply chain resilience."
Olin Corporation
Our Research Team & Methodology
Every Fundamental Business Insights report is built by a dedicated vertical research team, validated through a structured primary-and-secondary methodology, and reviewed for accuracy before it reaches you.
This report was prepared by the Chemicals & Materials Research Team at Fundamental Business Insights, a dedicated research group specializing in the global chemicals, advanced materials, and industrial manufacturing sectors. Our analysts continuously monitor raw material supply chains, feedstock pricing, production technologies, regulatory developments, sustainability initiatives, environmental compliance, trade dynamics, and evolving end-use applications to deliver timely and reliable market intelligence. The research is developed using a structured methodology that combines primary discussions with manufacturers, raw material suppliers, distributors, and industry experts, along with company annual reports, regulatory publications, government trade statistics, industry associations, technical literature, patent databases, and other authoritative secondary sources. Market estimates are validated through multiple research techniques, including top-down and bottom-up analysis, before undergoing an internal quality review to ensure accuracy, consistency, and methodological integrity prior to publication.
Delivery
Published
Available
Support
- Market Size & Forecast
- Market Segmentation
- Regional Analysis
- Growth Drivers & Challenges
- Market Dynamics
- Competitive Landscape
- Company Profiles
- Competitive Benchmarking
- Mergers & Acquisitions
- Market Share Analysis or Key Company Strategies
- Value Chain Analysis
- Porter's Five Forces
- PESTLE Analysis
- Pricing Trends
- Supply-Demand Analysis
- Technology Landscape
- Regulatory Landscape
- Investment & Funding Landscape
- Emerging Opportunities
- Future Market Outlook