Automotive Semiconductor Market Size & Growth Forecast 2027–2036, By Segments (Vehicle Type, Application, Component), Regional Demand Trends (North America, Asia Pacific, Europe), Key Country Insights (U.S., Japan, South Korea, Germany, France, Italy), and Competitive Landscape
Jump to Content
Market Size and Growth Outlook
Automotive Semiconductor Market size was assessed at USD 67.2 billion in 2026 and is poised to grow at a 11.21% CAGR between 2027 and 2036, exceeding USD 194.45 billion by 2036. The industry revenue for 2027 is calculated at USD 73.54 billion.
Get more details on this report
Request Free Sample ReportAutomotive Semiconductor Market Intelligence Snapshot
Regional Market Dynamics
- Asia Pacific accounted for the largest share of the automotive semiconductor market in 2026, driven by its strong automotive manufacturing ecosystem, extensive electronics supply chain, concentration of vehicle production, and growing demand for advanced automotive technologies.
- Asia Pacific is the fastest-growing region, supported by rising electric vehicle adoption, increasing integration of advanced driver-assistance systems, vehicle connectivity, infotainment technologies, and investments in automotive electronics manufacturing and semiconductor capabilities.
Segment Momentum
- The passenger vehicle segment accounts for 64.02% of the automotive semiconductor market in 2026, driven by increasing integration of electronic components across advanced driver assistance systems (ADAS), infotainment, connectivity, power management, and vehicle control systems.
- The safety segment is expected to grow at the fastest pace, supported by increasing adoption of advanced driver assistance systems (ADAS), collision avoidance technologies, automatic emergency braking, electronic stability control, and driver monitoring systems.
Market Expansion Drivers
- Rising electric and hybrid vehicle production increasing demand for advanced automotive semiconductors.
- Expanding ADAS and active safety system integration accelerating semiconductor sensor deployment.
- Increasing connected vehicle and onboard diagnostics adoption strengthening ECU semiconductor requirements.
Leading Market Participants
- Key companies in the automotive semiconductor market include Infineon Technologies AG (Germany), NXP Semiconductors N.V. (Netherlands), Renesas Electronics Corporation (Japan), Robert Bosch GmbH (Germany), Texas Instruments Incorporated (United States), Analog Devices, Inc. (United States), STMicroelectronics N.V. (Switzerland), ON Semiconductor Corporation (United States), Qualcomm Incorporated (United States), Intel Corporation (United States).
Global Market Forecast Snapshot
Market Outlook
- 2026 Market Size: USD 67.2 billion
- 2027 Estimated Market Size: USD 73.54 billion.
- Projected Market Size: USD 194.45 billion by 2036
- Growth Forecast: 11.21% CAGR (2027-2036)
Regional and Segment Outlook
- Leading Regional Market: Asia Pacific
- High-Growth Regional Hub: Asia Pacific
- Core Revenue Segment: Passenger Vehicle (Vehicle Type) | Body Electronics (Application) | Processor (Component)
- Emerging Opportunity Segment: Passenger Vehicle (Vehicle Type) | Safety (Application) | Discrete Power (Component)
Market Growth Drivers and Industry Trends
Rising electric and hybrid vehicle production increasing demand for advanced automotive semiconductors
The automotive semiconductor market is expanding as electric and hybrid vehicle production increases the need for electronic components across propulsion, battery management, power conversion, and vehicle control systems. Electrified powertrains rely on semiconductor devices to manage energy flows, monitor system conditions, and control electrical functions with precision. Greater electronic content in these vehicles therefore increases semiconductor requirements across power management and other core vehicle architectures.
Expanding ADAS and active safety system integration accelerating semiconductor sensor deployment
Expansion of advanced driver assistance and active safety systems is accelerating the automotive semiconductor market by increasing the number of sensors and processing components required for vehicle perception and control. ADAS functions depend on semiconductor-enabled cameras, radar, sensing modules, processors, and control units to detect surrounding conditions and support automated safety responses. As vehicle manufacturers integrate more sophisticated assistance features, semiconductor content becomes increasingly important to the operation of these safety systems.
Increasing connected vehicle and onboard diagnostics adoption strengthening ECU semiconductor requirements
The growing adoption of connected vehicles and onboard diagnostics is reinforcing the automotive semiconductor market as vehicles increasingly depend on electronic control units to manage communication, monitoring, and diagnostic functions. ECUs process information from multiple vehicle systems and facilitate communication between sensors, controllers, and connected services, increasing the need for reliable semiconductor components. Greater vehicle connectivity also expands the volume of electronic functions that require real-time processing and system-level coordination.
| Growth Driver | Impact on CAGR | Regulatory Influence | Geographic Relevance | Adoption Rate | Impact Timeline |
|---|---|---|---|---|---|
| Rising electric and hybrid vehicle production increasing demand for advanced automotive semiconductors | 2.00% | High | Asia Pacific, Europe, North America | High | Near Term |
| Expanding ADAS and active safety system integration accelerating semiconductor sensor deployment | 1.80% | High | North America, Europe, Asia Pacific | High | Near Term |
| Increasing connected vehicle and onboard diagnostics adoption strengthening ECU semiconductor requirements | 1.30% | Moderate | Asia Pacific, North America | Medium | Mid Term |
Explore Growth Opportunities
Request Free Sample ReportRegional Demand Dynamics
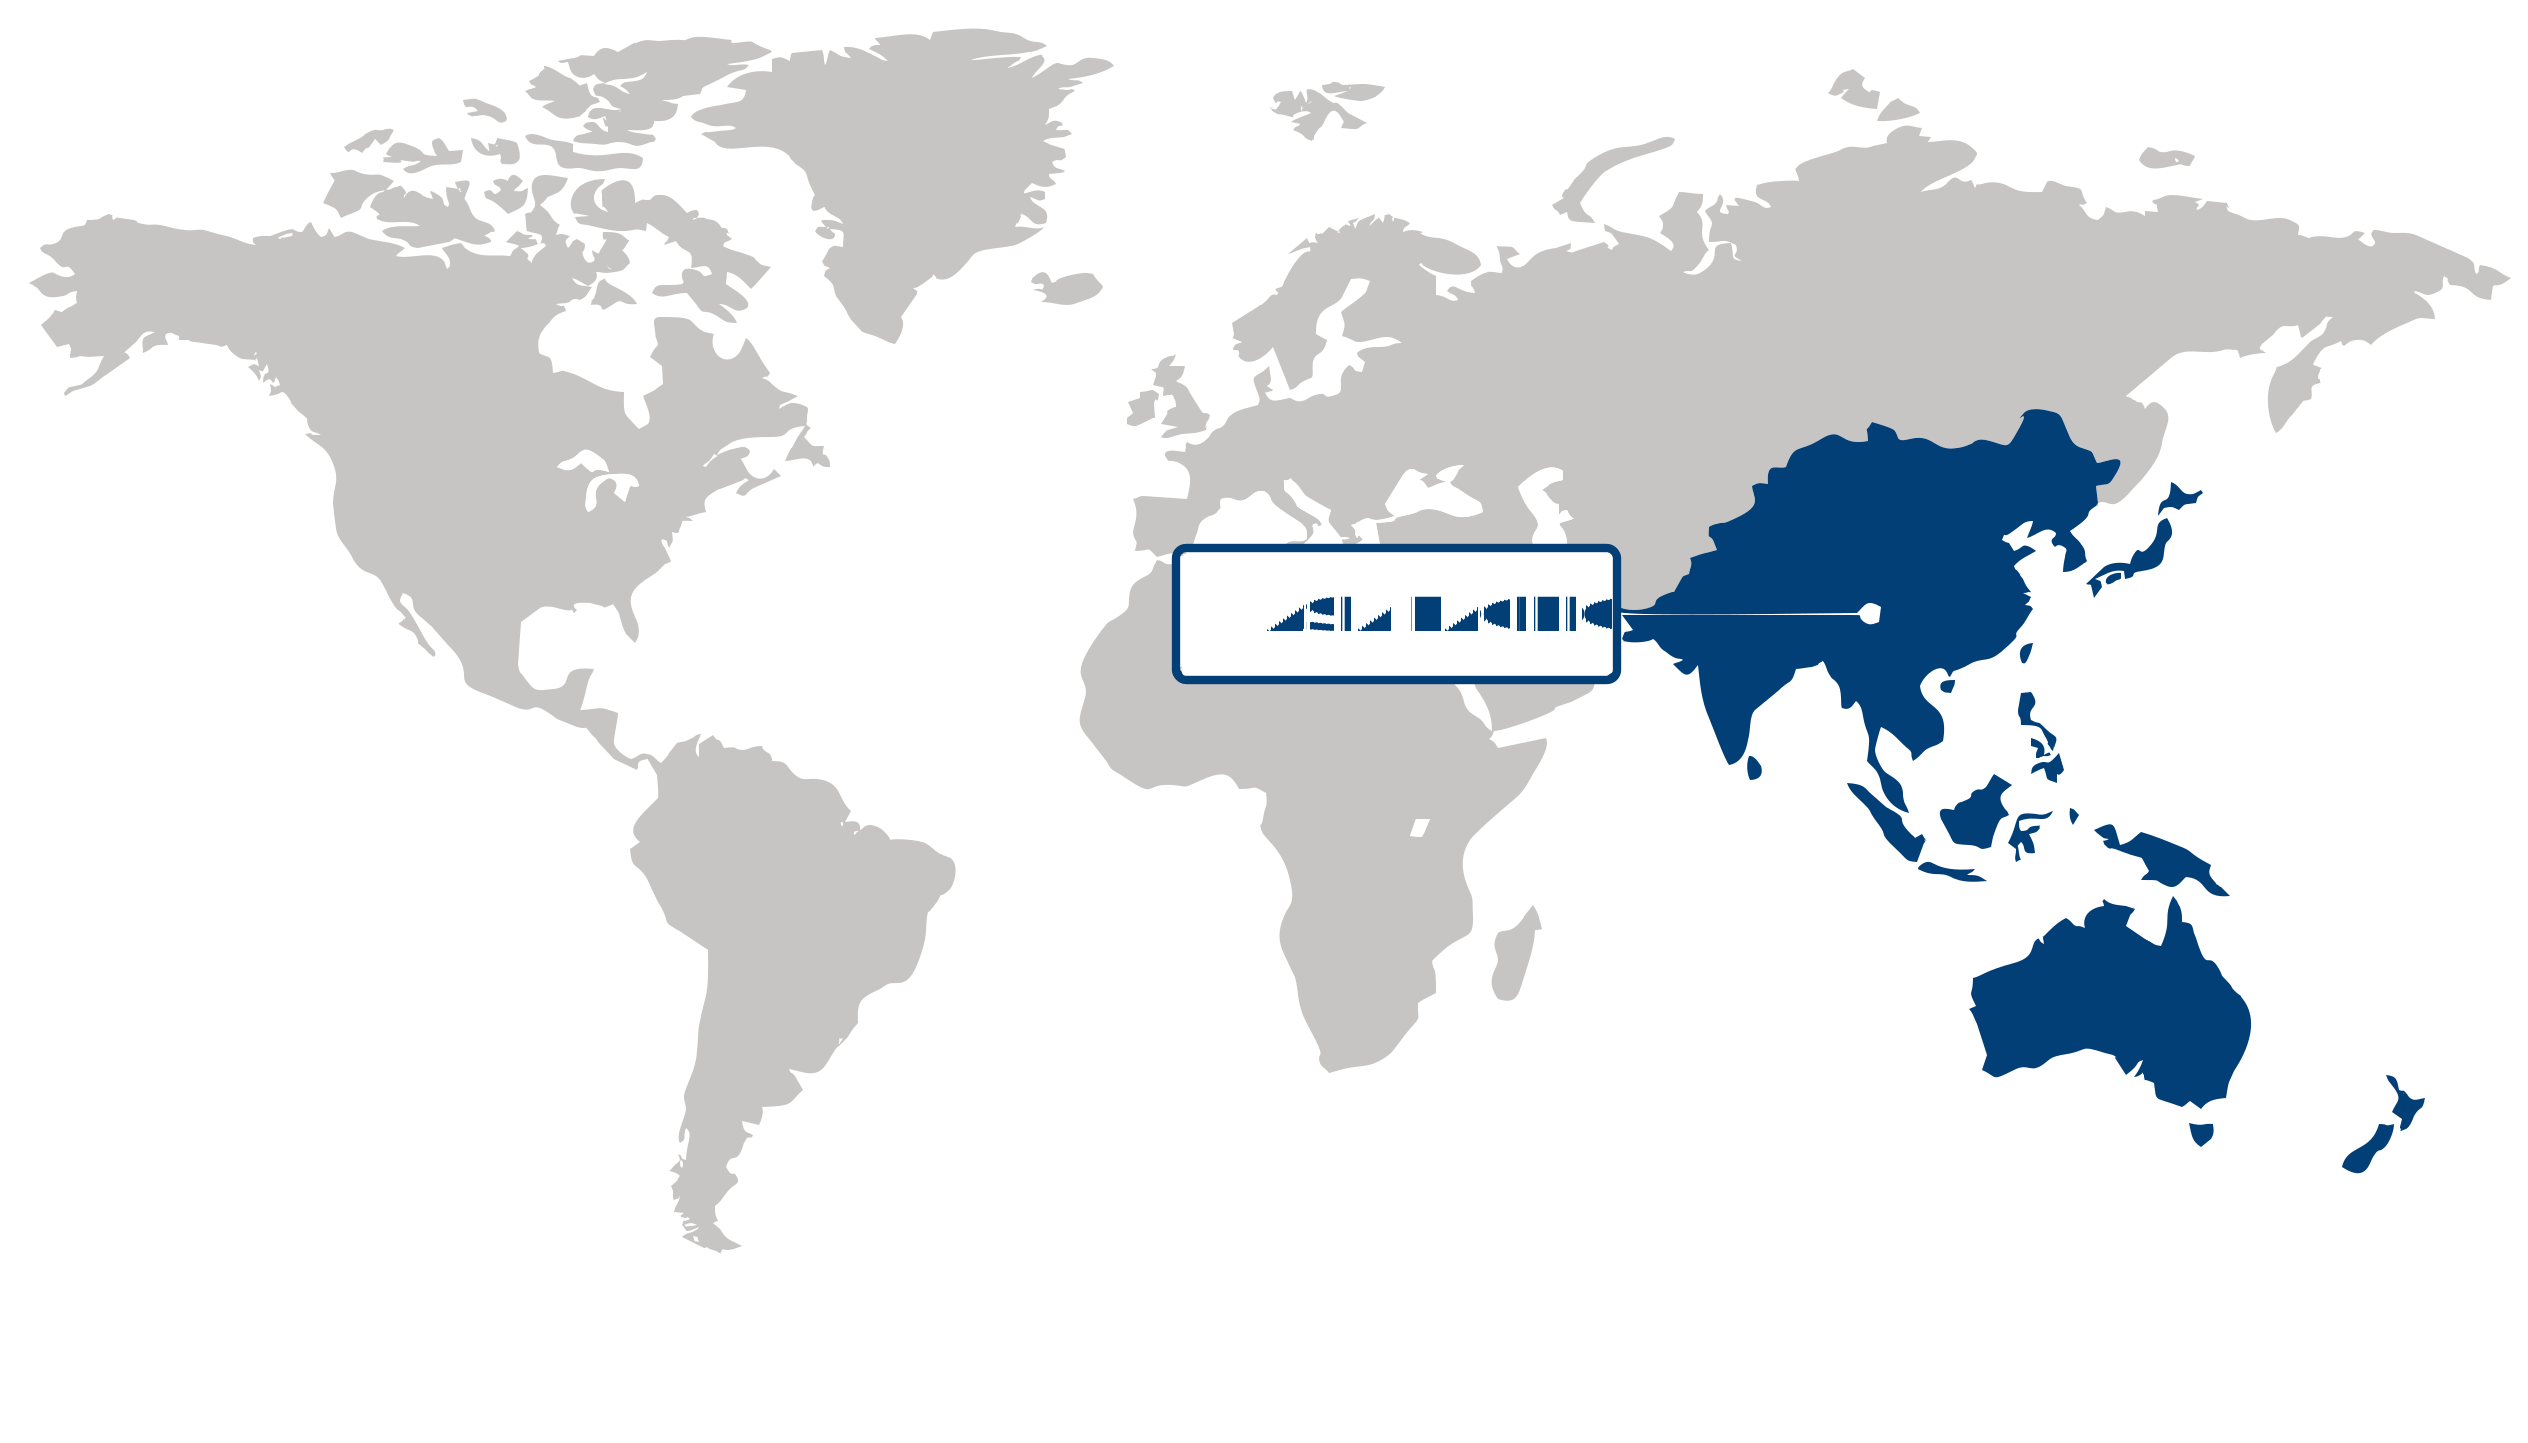
Asia Pacific (Largest & Fastest-Growing Region)
Asia Pacific accounted for the largest share of the automotive semiconductor market in 2026 and is also projected to be the fastest-growing region. The region's strong automotive manufacturing ecosystem, extensive electronics supply chain, and concentration of vehicle and component production are driving demand for automotive semiconductors. Increasing adoption of electric vehicles, advanced driver-assistance systems, infotainment, vehicle connectivity, and software-intensive vehicle architectures is further accelerating market growth. Additionally, rising investments in automotive electronics manufacturing, semiconductor capabilities, and domestic technology development are strengthening the regional supply chain. The growing emphasis on vehicle electrification, high-performance computing, and advanced mobility technologies is expected to create significant opportunities for automotive semiconductor manufacturers across the region.
| Parameter | North America | Asia Pacific | Europe | Latin America | MEA |
|---|---|---|---|---|---|
| Innovation HubiScaleNascentDeveloping Advanced | |||||
| Cost-Sensitive RegioniScaleLowMedium High | |||||
| Regulatory EnvironmentiScaleRestrictiveNeutral Supportive | |||||
| Demand DriversiScaleWeakModerate Strong | |||||
| Development StageiScaleEmergingDeveloping Developed | |||||
| Adoption RateiScaleLowMedium High | |||||
| New Entrants / StartupsiScaleSparseModerate Dense | |||||
| Macro IndicatorsiScaleWeakStable Strong |
Key Country Insights
Germany 🇩🇪
Functional Safety IntegrationGermany emphasizes automotive semiconductors designed for powertrain control, safety systems, and industrial-grade reliability. German automakers and suppliers prioritize certified semiconductor solutions that support increasingly sophisticated electronic vehicle platforms.
France 🇫🇷
Connected Mobility SystemsFrance supports automotive semiconductor adoption through connected mobility, intelligent transportation, and vehicle electronics modernization. French automotive companies increasingly integrate advanced semiconductor solutions to improve communication, safety, and electronic system performance.
Italy 🇮🇹
Automotive Electronics ModernizationItaly expands automotive semiconductor usage by modernizing vehicle electronics across passenger and commercial vehicle manufacturing. Italian suppliers prioritize reliable semiconductor integration for connectivity, control modules, and advanced safety applications within evolving vehicle platforms.
Japan 🇯🇵
Efficient Power ElectronicsJapan advances automotive semiconductor development through power management, sensor integration, and vehicle efficiency applications. Japanese manufacturers concentrate on dependable semiconductor technologies that enhance electrified vehicle performance and long-term operational stability.
South Korea 🇰🇷
EV Electronics ExpansionSouth Korea accelerates automotive semiconductor adoption across electric vehicles, infotainment, and battery management systems. South Korean manufacturers invest in semiconductor capabilities that improve system integration, energy efficiency, and digital vehicle functionality.
United States 🇺🇸
Intelligent Vehicle ElectronicsThe U.S. automotive semiconductor market focuses on chips supporting autonomous driving, vehicle connectivity, and advanced driver assistance systems. U.S. technology companies prioritize high-performance semiconductor platforms that enable software-defined vehicle architectures and reliable electronic control systems.
Automotive Semiconductor Market Share (%), by Vehicle Type, 2026
Go beyond the chart, access full insights & data tables
Request Free Sample ReportVehicle Type Segment Analysis: Passenger Vehicles (Largest & Fastest-Growing Segment)
The passenger vehicle segment represents the largest and fastest-growing vehicle type in the automotive semiconductor market, accounting for a 64.02% market share in 2026. Its leading position is supported by the increasing integration of electronic components into modern vehicles to enhance safety, connectivity, comfort, power management, and driving performance. The growing adoption of advanced driver assistance systems (ADAS), infotainment platforms, vehicle connectivity, and intelligent power management solutions is increasing semiconductor requirements across passenger vehicle architectures. Rising consumer demand for connected, technologically advanced, and feature-rich vehicles is further accelerating the integration of sensors, processors, microcontrollers, memory devices, and power semiconductors. Additionally, the transition toward electric vehicles and software-defined vehicles is creating new opportunities for semiconductor integration across battery management, powertrain control, vehicle networking, and autonomous driving technologies. Continuous advancements in automotive electronics and increasing investments in vehicle electrification and intelligent mobility are expected to reinforce the segment's dominant position and support its fastest-growing status in the automotive semiconductor market.
Application Segment Analysis: Body Electronics (Largest Segment) vs Safety (Fastest-Growing Segment)
Body electronics held the largest share of the automotive semiconductor market at 24.84% in 2026, supported by the extensive use of electronic components in lighting, climate control, power windows, access systems, seat controls, and other vehicle body functions. Growing expectations for convenience, comfort, and automated functionality are increasing the number and sophistication of electronic systems integrated throughout vehicle interiors and exteriors. The continued electrification and digitalization of vehicle architectures are further supporting demand for semiconductors used in body control applications.
The safety segment is anticipated to be the fastest-growing application category as automakers increasingly integrate advanced electronic technologies to improve vehicle safety, prevent accidents, and enhance driver and passenger protection. The growing adoption of advanced driver assistance systems (ADAS), electronic stability control, collision avoidance systems, automatic emergency braking, airbag control units, and driver monitoring technologies is increasing semiconductor requirements across automotive safety applications. Rising regulatory emphasis on vehicle safety standards, growing consumer awareness, and increasing demand for intelligent safety features are further accelerating adoption. Continuous advancements in sensors, microcontrollers, processors, and real-time vehicle monitoring technologies are expected to support strong growth in semiconductor demand across the safety segment.
| Segment | Sub-Segment | Largest Segment | Fastest Growing |
|---|---|---|---|
| Vehicle Type | Passenger Vehicle, Light Commercial Vehicle (LCV), Heavy Commercial (HCV) | Passenger Vehicle | Passenger Vehicle |
| Application | Chassis, Powertrain, Safety, Telematics & Infotainment, Body Electronics | Body Electronics | Safety |
| Component | Processor, Discrete Power, Sensor, Memory, Others | Processor | Discrete Power |
Unlock insights tailored to your business with our bespoke market research solutions.
Click to get your customized report now.
Competitive Landscape and Market Positioning
Key companies in the automotive semiconductor market:
1. Infineon Technologies AG (Germany)
2. NXP Semiconductors N.V. (Netherlands)
3. Renesas Electronics Corporation (Japan)
4. Robert Bosch GmbH (Germany)
5. Texas Instruments Incorporated (United States)
6. Analog Devices Inc. (United States)
7. STMicroelectronics N.V. (Switzerland)
8. ON Semiconductor Corporation (United States)
9. Qualcomm Incorporated (United States)
10. Intel Corporation (United States)
The automotive semiconductor market is experiencing strong growth due to rising adoption of electric vehicles, connected mobility solutions, and autonomous driving technologies. Companies are emphasizing high-performance chipsets, power management systems, and AI-enabled automotive electronics to support evolving vehicle architectures. Increasing software-defined vehicle development is also accelerating technological innovation across the market.
| Company | Market Share | Company Revenue | Revenue CAGR (%) | Product Portfolio | Geographic Presence | Innovation / R&D Focus | Strategic Developments |
|---|---|---|---|---|---|---|---|
| Infineon Technologies AG (Germany) | |||||||
| NXP Semiconductors N.V. (Netherlands) | |||||||
| Renesas Electronics Corporation (Japan) | |||||||
| Robert Bosch GmbH (Germany) | |||||||
| Texas Instruments Incorporated (United States) | |||||||
| Analog Devices Inc. (United States) | |||||||
| STMicroelectronics N.V. (Switzerland) | |||||||
| ON Semiconductor Corporation (United States) | |||||||
| Qualcomm Incorporated (United States) | |||||||
| Intel Corporation (United States). |
Industry Development/News
| Company Name | Date | Key Development |
|---|---|---|
| Denso | Mar-26 | Denso announced plans to acquire ROHM Semiconductor for approximately 1.3 trillion yen. This strategic move aims to bolster capabilities in electric vehicle and AI semiconductor technologies, enhance critical supply chain security, and significantly improve Denso's competitive positioning within the global automotive semiconductor sector. |
| Boss Semiconductor | Feb-26 | Boss Semiconductor secured KRW 87 billion in funding to scale production and development of mobility AI chips. This capital injection supports its geographic expansion efforts and strengthens its market position in automotive semiconductor applications, with a specific focus on capturing growth opportunities within the Chinese automotive sector. |
| Guoxin Micro | Dec-25 | Guoxin Micro spun off its automotive controller chip business, incorporating a CATL subsidiary as a strategic shareholder. This restructuring enhances the business unit's funding capacity and operational flexibility, positioning it to capitalize on increasing demand for semiconductors driven by the rapid adoption of electric and intelligent vehicles. |
| ROHM Semiconductor | Dec-25 | ROHM Semiconductor established a partnership with Tata Electronics to manufacture power semiconductors and automotive devices in India. This collaboration is designed to strengthen global production capacity and expand supply chain resilience, addressing the increasing demand for high-performance automotive components in international markets. |
| Hyundai Mobis | Oct-25 | Hyundai Mobis launched Auto Semicon Korea in collaboration with 23 industry partners. This initiative aims to strengthen South Korea’s domestic automotive semiconductor ecosystem by reducing reliance on imported components and accelerating the development of localized semiconductor innovation for next-generation vehicle applications. |
| LG Innotek | Mar-25 | LG Innotek entered the automotive application processor module market, expanding its semiconductor component portfolio. This strategic expansion is designed to address the growing demand from advanced driver assistance systems and digital cockpit platforms, marking a significant move to strengthen its competitive standing in modern vehicle electronics. |
| Honda | Jan-25 | Honda entered a partnership with Renesas Electronics to co-develop high-performance automotive chips for next-generation electric vehicles. The collaboration targets advanced autonomous driving functions, leveraging leading-edge semiconductor manufacturing technology to drive innovation in vehicle electronics and improve operational capabilities for future vehicle platforms. |
| Infineon Technologies | Nov-24 | Infineon Technologies signed a long-term semiconductor supply and capacity agreement with Stellantis to support future electric vehicle generations. The partnership secures strategic chip supply for vehicle electrification programs, reinforcing Infineon's role in the automotive value chain and supporting the transition to electrified transportation platforms. |
| SK keyfoundry | May-24 | SK keyfoundry secured a contract to manufacture power semiconductors for Tesla. This agreement represents a strategic expansion of its automotive semiconductor business and enhances its presence within the electric vehicle supply chain, reflecting broader industry efforts to scale production capacity for critical power management components. |
| Amkor Technology | Apr-24 | Amkor Technology and Infineon Technologies formed a multi-year partnership to establish a dedicated semiconductor packaging and test center in Porto, Portugal. This facility is intended to enhance European semiconductor supply chain resilience and provide specialized support for automotive semiconductor production requirements. |
Customize Your Report
Explore examples of how this report can be tailored to different research needs, including custom segments, additional topics or chapters, and related reports. Click a section of the wheel or its numbered marker to explore the available options.
Automotive Semiconductor Market — Custom Segments
| Segment | Sub-Segment |
|---|---|
| Propulsion Type | Internal Combustion Engine, Hybrid Electric Vehicle, Plug-in Hybrid Electric Vehicle, Battery Electric Vehicle, Fuel Cell Electric Vehicle |
| Level of Vehicle Autonomy | Non-Autonomous, Driver Assistance, Level 2, Level 3, Level 4–5 |
| Sales Channel | Direct OEM Supply, Tier-1 Supplier Supply, Distributor & Electronics Supplier, Aftermarket |
Automotive Semiconductor Market — Custom TOC
| Custom Chapter | Chapter Details |
|---|---|
| Automotive Chip Supply Chain Resilience Assessment |
|
| Software-Defined Vehicle Semiconductor Roadmap |
|
| Vehicle Electronics Content Evolution Analysis |
|
Need a different cut of the data?
Request Custom ResearchFrequently Asked Questions
How much revenue does the automotive semiconductor market generate?
How much is the automotive semiconductor industry expected to grow by 2036?
How is vehicle electrification influencing semiconductor sourcing strategies?
Why are ADAS and connected vehicle technologies accelerating semiconductor demand?
Why does the passenger vehicle segment hold the largest share of the automotive semiconductor market?
Which application segment is expected to grow the fastest in the automotive semiconductor market?
Why does Asia Pacific lead the automotive semiconductor market?
Why is Asia Pacific the fastest-growing region in the automotive semiconductor market?
What are the prominent companies operating in the automotive semiconductor landscape?
Our Clients
"The team surpassed our expectations with the report depth. The actionable insights provided proved crucial in navigating market challenges."
Tata Motors
"We found the report to be very informative. The expertise and attention to market nuances significantly influenced our business direction."
DENSO Corporation
"The consumer survey findings were quite good. We now have a clearer picture of the customer churning and retention strategy."
HL Mando
Our Research Team & Methodology
Every Fundamental Business Insights report is built by a dedicated vertical research team, validated through a structured primary-and-secondary methodology, and reviewed for accuracy before it reaches you.
This report was prepared by the Automotive & Transportation Research Team at Fundamental Business Insights, a dedicated research group specializing in the global automotive, mobility, and transportation industries. Our analysts continuously monitor vehicle technology advancements, electrification trends, autonomous and connected mobility, manufacturing developments, supply chain dynamics, regulatory standards, emissions policies, aftermarket activities, and evolving consumer and commercial transportation requirements to deliver timely and reliable market intelligence. The research is developed using a structured methodology that combines primary discussions with vehicle manufacturers, component suppliers, technology providers, distributors, logistics stakeholders, and industry experts, along with company annual reports, regulatory publications, government transportation statistics, industry associations, technical standards, and other authoritative secondary sources. Market estimates are validated through multiple research techniques, including top-down and bottom-up analysis, before undergoing an internal quality review to ensure accuracy, consistency, and methodological integrity prior to publication.
Delivery
Published
Available
Support
- Market Size & Forecast
- Market Segmentation
- Regional Analysis
- Growth Drivers & Challenges
- Market Dynamics
- Competitive Landscape
- Company Profiles
- Competitive Benchmarking
- Mergers & Acquisitions
- Market Share Analysis or Key Company Strategies
- Value Chain Analysis
- Porter's Five Forces
- PESTLE Analysis
- Pricing Trends
- Supply-Demand Analysis
- Technology Landscape
- Regulatory Landscape
- Investment & Funding Landscape
- Emerging Opportunities
- Future Market Outlook