Oral Antidiabetic Drugs Market Size & Forecasts 2026-2035, By Segments (Type, End User, Drugs Class), Growth Opportunities, Innovation Landscape, Regulatory Shifts, Strategic Regional Insights (U.S., Japan, China, South Korea, UK, Germany, France), and Competitive Dynamics (Novartis, Sanofi, Eli Lilly, Merck, AstraZeneca)
Jump to Content
Market Size and Growth Outlook
Oral Antidiabetic Drugs Market size is likely to expand from USD 48.07 billion in 2025 to USD 74.65 billion by 2035, posting a CAGR above 4.5% across 2026-2035. The industry’s revenue potential for 2026 is USD 49.93 billion.
Get more details on this report
Request Free Sample ReportOral Antidiabetic Drugs Market Intelligence Snapshot
Regional Market Dynamics
Segment Momentum
Market Expansion Drivers
Leading Market Participants
Global Market Forecast Snapshot
Market Outlook
Regional and Segment Outlook
Market Growth Drivers and Industry Trends
The rising global incidence of diabetes is a critical growth driver for the oral antidiabetic drugs market, driven by lifestyle changes and demographic trends such as aging populations and urbanization. The World Health Organization reports a steady increase in diabetes cases worldwide, underscoring the expanding patient pool requiring consistent glucose management. This growing demand compels pharmaceutical companies and healthcare providers to prioritize accessible and effective oral treatments over more invasive options, reshaping competitive dynamics. Established firms can leverage scale and brand trust to broaden geographic reach, while new entrants may capitalize on niche segments and emerging markets. As prevalence patterns persist, the oral antidiabetic drugs market is set to evolve into a key healthcare sector emphasizing innovation in patient adherence solutions and cost containment.
Introduction of Novel Oral Antidiabetic Drugs
Innovation in drug formulation and mechanism of action has significantly impacted the oral antidiabetic drugs market, with leading pharmaceutical players such as Novo Nordisk and Eli Lilly launching new classes like SGLT2 inhibitors and GLP-1 receptor agonists in oral forms. These advancements cater to unmet clinical needs for better efficacy and reduced side effects, responding to evolving patient expectations and prescriber preferences. Regulatory agencies including the U.S. Food and Drug Administration have accelerated approvals for such novel agents, signaling a shift towards more personalized diabetes management. This momentum offers strategic opportunities for innovators to establish differentiated portfolios, while incumbents can reinvest to upgrade their pipelines and marketing approaches. Going forward, continuous innovation will remain pivotal in sustaining competitive advantage within the oral antidiabetic drugs market.
Government Health Initiatives for Diabetes Management
Public health policies and government programs targeting diabetes prevention and management are intensifying focus on oral antidiabetic drugs as cost-effective therapeutic options. Agencies like the Centers for Disease Control and Prevention (CDC) in the U.S. and the National Health Commission of China emphasize early diagnosis and treatment adherence, facilitating wider patient access to oral therapies through insurance reimbursements and subsidy schemes. These frameworks incentivize pharmaceutical manufacturers to develop affordable drugs and engage in public-private partnerships, fostering scalability and outreach in underserved communities. Both established companies and new entrants can strategically align with these initiatives to enhance market penetration and foster trust among healthcare providers and patients. This trend points to sustained policy support that will underpin the oral antidiabetic drugs market’s expansion in the coming years.
Industry Restraints:
Stringent Regulatory Approval Processes
The oral antidiabetic drugs market faces significant delays and increased costs due to rigorous regulatory approval requirements across key markets such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA). These agencies enforce exhaustive clinical trials to ensure safety, efficacy, and pharmacovigilance of antidiabetic compounds, often extending development timelines and constraining the speed at which innovative therapies reach patients. For example, the prolonged review cycle documented by the FDA’s Center for Drug Evaluation and Research (CDER) has delayed the introduction of newer classes like SGLT2 inhibitors in certain regions. This regulatory complexity imposes substantial entry barriers for smaller biopharmaceutical firms, concentrates market power among incumbents with ample resources, and hampers portfolio diversification. Moving forward, unless regulatory frameworks adapt to foster expedited but safe approvals—such as through adaptive licensing or real-world evidence incorporation—this barrier will continue to slow market dynamism and restrict rapid drug innovation dissemination.
Rising Drug Pricing Pressures and Reimbursement Challenges
Escalating scrutiny of pharmaceutical pricing, particularly within government healthcare programs like Medicare and international payers such as Germany’s Federal Joint Committee (G-BA), is constraining oral antidiabetic drug market expansion. Heightened policy efforts to control spending—evidenced in the Centers for Medicare & Medicaid Services’ (CMS) reimbursement caps and pricing negotiations—limit manufacturers’ pricing flexibility, especially for novel branded agents. This dynamic dampens investment incentives in R&D by reducing expected returns, while also fueling market fragmentation as payers favor cost-effective generics and older, established medications. For new entrants, the stringent reimbursement landscape complicates market penetration strategies, often necessitating value-based pricing models or outcome-linked agreements. Unless innovative contracting mechanisms become more widely embraced, pricing and reimbursement pressures will continue to restrain market growth and may accelerate competitive consolidation in the oral antidiabetic segment.
| Growth Driver | Impact on CAGR | Regulatory Influence | Geographic Relevance | Adoption Rate | Impact Timeline |
|---|---|---|---|---|---|
| Increasing Diabetes Prevalence | 2.00% | Short term (≤ 2 yrs) | North America, Europe | Medium | Fast |
| Introduction of Novel Oral Antidiabetic Drugs | 1.50% | Medium term (2–5 yrs) | North America, Asia Pacific | High | Moderate |
| Government Health Initiatives for Diabetes Management | 1.00% | Long term (5+ yrs) | Europe, Asia Pacific | High | Moderate |
Unlock insights tailored to your business with our bespoke market research solutions.
Click to get your customized report now.
Regional Demand Dynamics
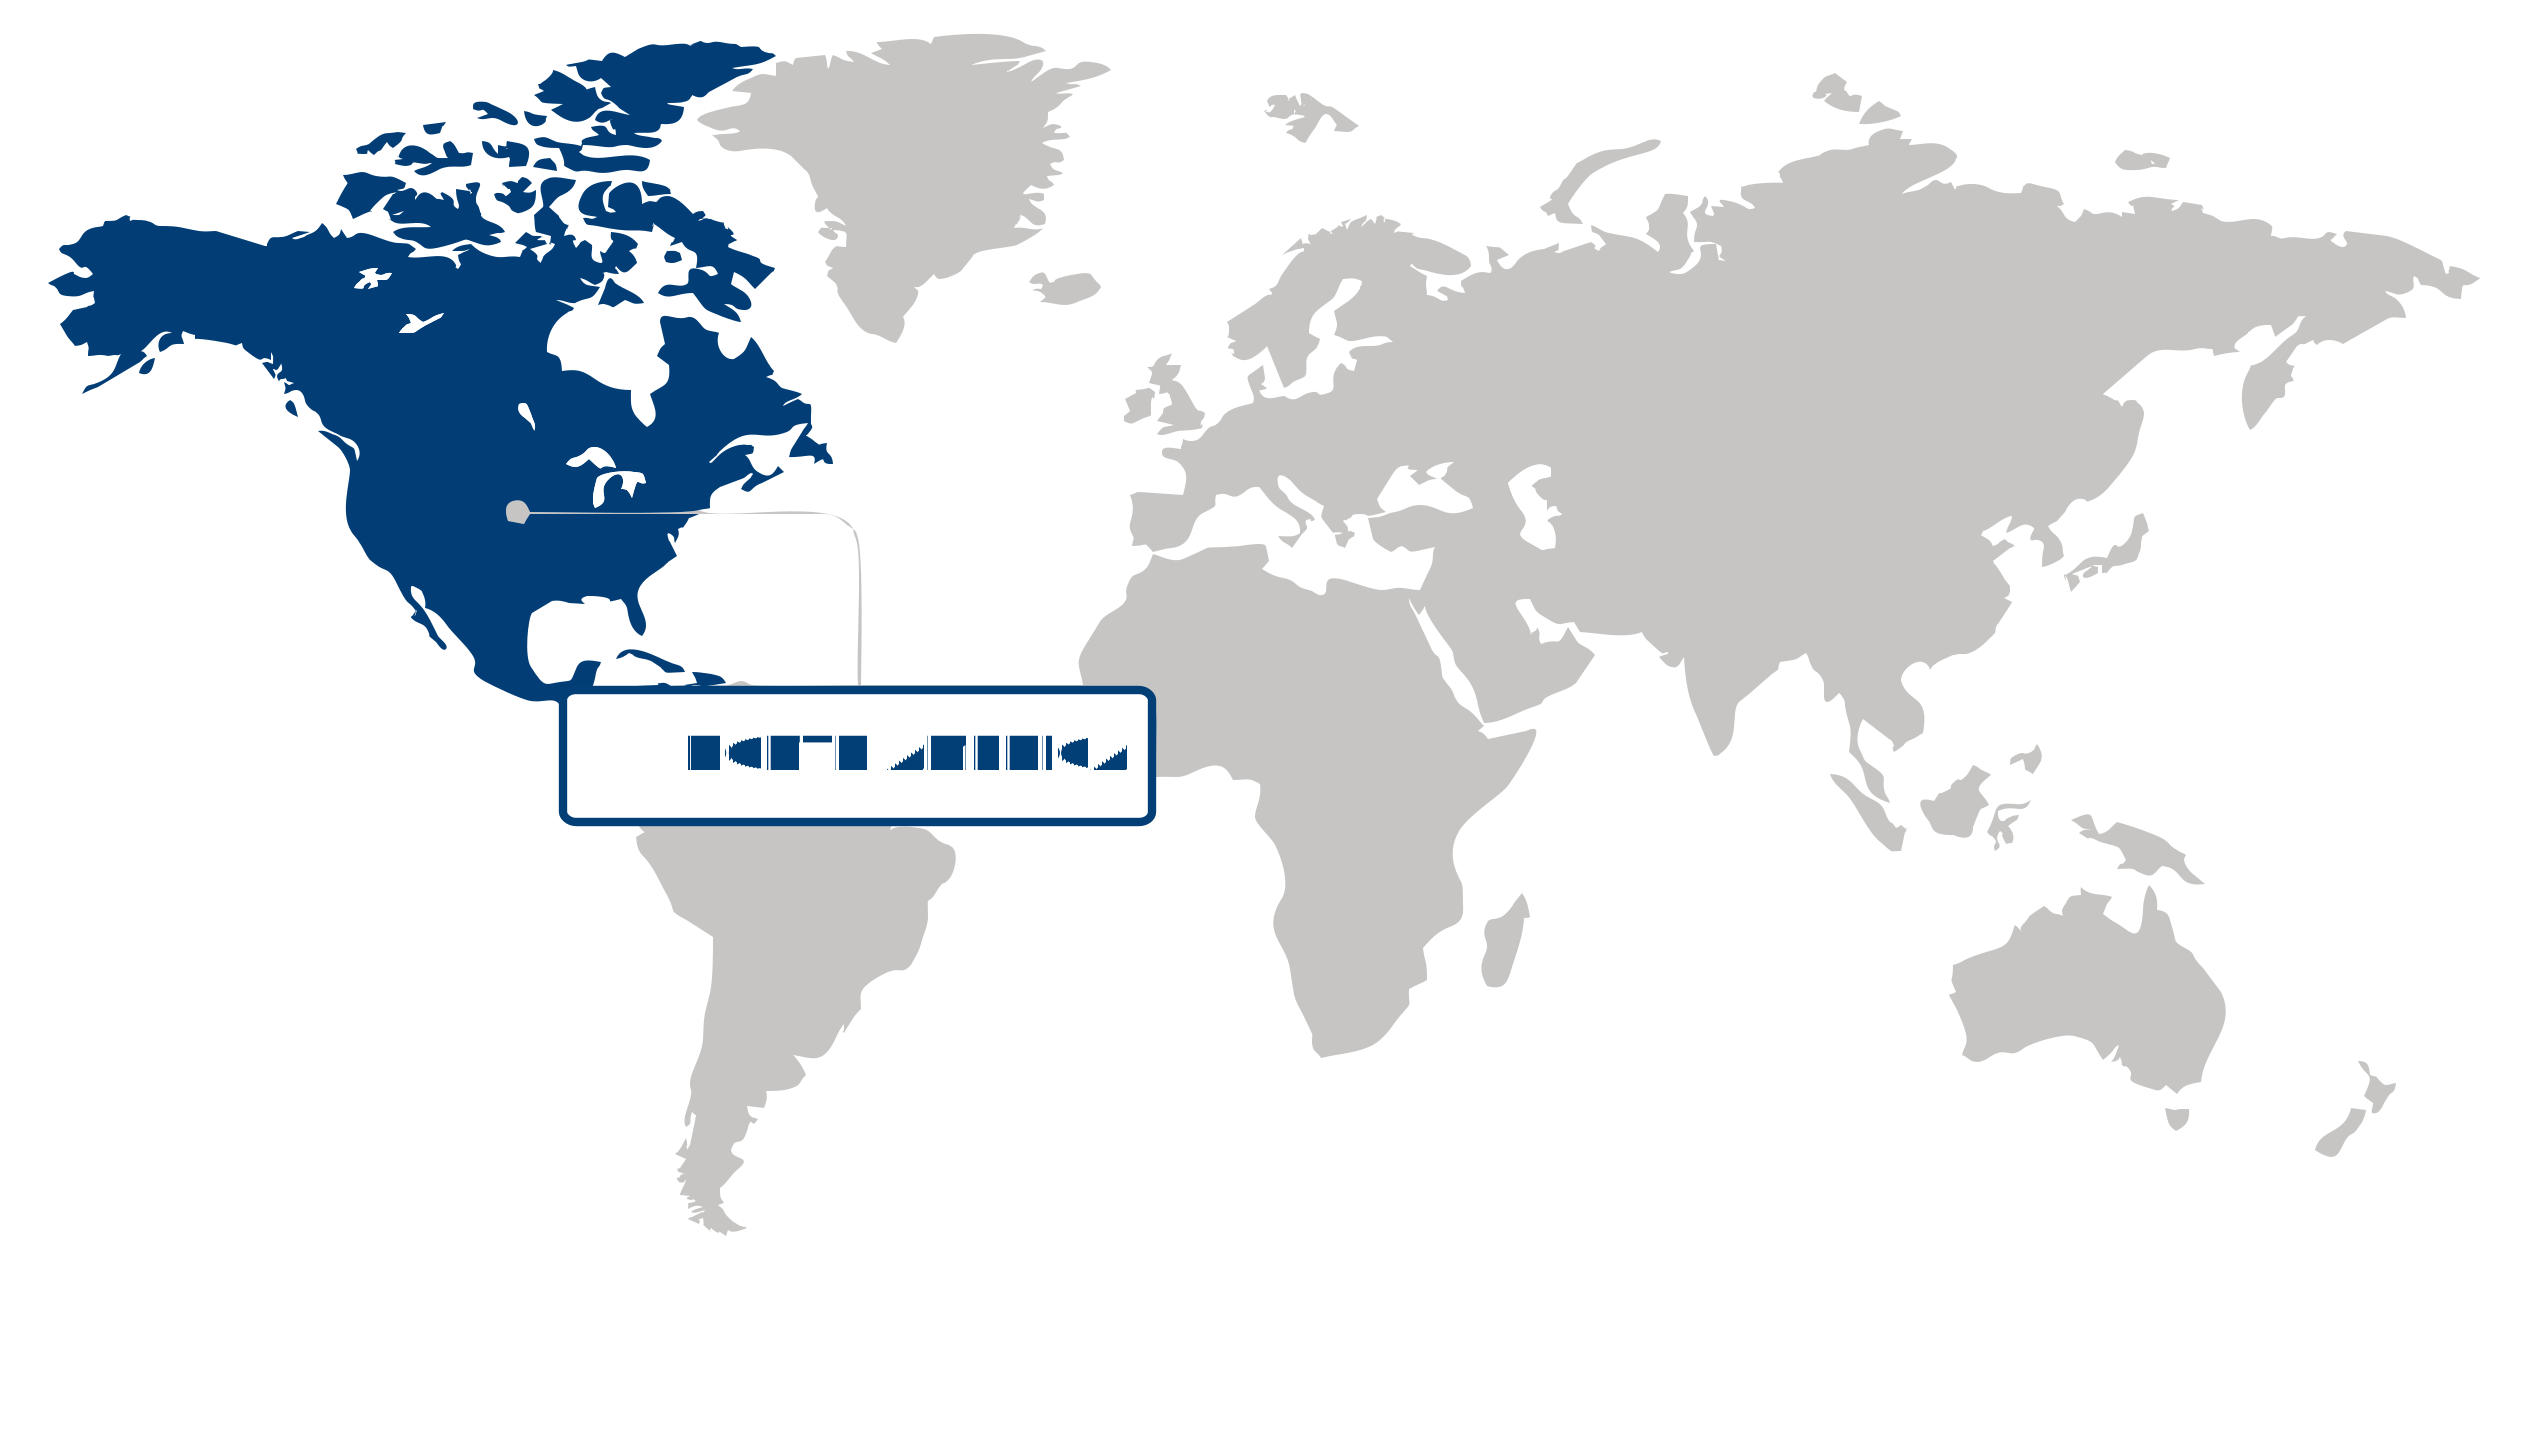
North America represents more than 43% of the global oral antidiabetic drugs market in 2025, making it the largest regional contributor. This leadership is primarily fueled by the high prevalence of type-2 diabetes combined with robust access to prescription therapies. Healthcare infrastructure advances, such as streamlined patient access programs and insurer coverage expansions, have enhanced treatment penetration. According to the Centers for Disease Control and Prevention (CDC), rising diabetes incidence drives sustained demand, while regulatory agencies like the U.S. Food and Drug Administration (FDA) actively promote innovative drug approvals, supporting market expansion. Additionally, North America's economic resilience and digital health integration create an environment conducive to personalized diabetes management solutions. These factors collectively position North America as a strategic growth area, offering substantial opportunities for stakeholders in the oral antidiabetic drugs market as therapeutic advancements and patient-centric care continue to evolve.
The United States anchors the North American oral antidiabetic drugs market, reflecting the nation's critical role in global pharmaceutical innovation. The high diabetes burden, as detailed by the CDC, combined with comprehensive insurance frameworks such as Medicare and Medicaid, ensures widespread treatment adoption. Moreover, the FDA’s accelerated approvals for novel oral therapies have intensified competition, encouraging companies to enhance efficacy and safety profiles. Corporate initiatives from pharmaceutical leaders like Eli Lilly and Novo Nordisk emphasize tailored treatment regimens, broadening consumer appeal. This dynamic regulatory and healthcare environment in the U.S. bolsters market growth and reinforces North America’s dominance, presenting lucrative opportunities for investors and strategists focusing on efficient, high-impact diabetes interventions.
Asia Pacific Market Analysis:
Asia Pacific emerged as the fastest-growing region in the oral antidiabetic drugs market, registering a robust CAGR of 6.3%. This rapid growth is primarily driven by the region’s rapidly rising diabetic population alongside expanding healthcare access. Countries across Asia Pacific are witnessing increasing prevalence of diabetes due to urbanization, changing lifestyles, and aging demographics, which has intensified demand for effective oral antidiabetic solutions. Enhanced healthcare infrastructure and government initiatives to improve insurance coverage and accessibility have further accelerated market penetration, particularly in emerging economies. For instance, the Asia-Pacific Economic Cooperation (APEC) has highlighted several regional healthcare reforms aimed at reducing non-communicable diseases, including diabetes, which boosts both treatment uptake and patient adherence. The region also leverages technological advancements in drug formulation and distribution channels, creating a resilient supply network. These factors collectively position Asia Pacific as a fertile ground for sustained expansion and innovation in the oral antidiabetic drugs market moving forward.
Japan plays a pivotal role in Asia Pacific’s oral antidiabetic drugs market, characterized by its advanced healthcare system and aging population, which significantly elevates demand for diabetes management solutions. The country’s strong emphasis on precision medicine and continuous innovation in pharmaceutical R&D, supported by entities such as the Pharmaceuticals and Medical Devices Agency (PMDA), accelerates product development and approvals. Additionally, Japan’s healthcare policies encourage early diagnosis and intervention, boosting consumption of oral antidiabetic drugs. This environment stimulates competitive strategies centered on high-efficacy and tailored treatment options. Meanwhile, China’s vast population and rising middle class underpin its strategic importance within the Asia Pacific market. Government programs like the Healthy China 2030 initiative have expanded healthcare coverage and access, facilitating greater affordability and availability of diabetic treatments across urban and rural areas. Public awareness campaigns and digital health innovations have enhanced patient engagement in disease management. Together, these country-level dynamics reinforce Asia Pacific’s leading position, offering significant opportunities for investors and market players focused on scalable and adaptive diabetes care solutions.
Europe Market Trends:
Europe maintained a significant share in the oral antidiabetic drugs market, driven by its robust healthcare infrastructure and rising prevalence of diabetes among an aging population. The region's advanced pharmaceutical industry benefits from stringent regulatory frameworks, such as the European Medicines Agency’s enhanced approval processes, fostering high-quality drug development and market entry. Increasing patient awareness and government initiatives, including France’s National Diabetes Plan, have stimulated demand for innovative, patient-friendly oral therapies. Furthermore, Europe’s commitment to sustainability has prompted manufacturers to adopt greener production technologies, reinforcing its competitive edge. Strategic investments in digital health platforms and supply chain modernization are improving access and adherence to antidiabetic regimens. These dynamics, combined with steady economic resilience and cross-border collaboration, position Europe as a pivotal hub for growth and innovation in the oral antidiabetic drugs market.
Germany plays a central role in the oral antidiabetic drugs market as Europe’s largest pharmaceutical market, supported by a highly developed healthcare system and comprehensive reimbursement models that facilitate patient access to novel therapies. Consumer preference trends reflect growing demand for personalized medicine and fixed-dose combinations, highlighted by Boehringer Ingelheim’s recent launch of combination treatments targeting type 2 diabetes. The German government's emphasis on digital health adoption, illustrated by the Federal Institute for Drugs and Medical Devices’ endorsement of digital apps for diabetes management, further accelerates market expansion. This integration of technology with traditional care underscores Germany’s strategic importance, enabling pharmaceutical companies to tailor offerings and capture increased market share within Europe.
France remains a critical contributor to Europe’s oral antidiabetic drugs market, supported by extensive public health programs and proactive regulatory frameworks that address rising diabetes incidence. The French Ministry of Health’s emphasis on early diagnosis and multidisciplinary care has enhanced patient outcomes, increasing demand for innovative oral antidiabetic drugs. Sanofi’s ongoing R&D investments in France, coupled with collaborations with research institutes like Inserm, demonstrate strong innovation capabilities that shape therapeutic advancements. Additionally, France’s cultural inclination toward preventive healthcare and lifestyle management complements pharmaceutical strategies, fostering sustained market growth. These factors solidify France’s position within Europe’s evolving landscape, providing key opportunities for market players targeting oral antidiabetic drugs.
| Parameter | North America | Asia Pacific | Europe | Latin America | MEA |
|---|---|---|---|---|---|
| Innovation HubiScaleNascentDeveloping Advanced | |||||
| Cost-Sensitive RegioniScaleLowMedium High | |||||
| Regulatory EnvironmentiScaleRestrictiveNeutral Supportive | |||||
| Demand DriversiScaleWeakModerate Strong | |||||
| Development StageiScaleEmergingDeveloping Developed | |||||
| Adoption RateiScaleLowMedium High | |||||
| New Entrants / StartupsiScaleSparseModerate Dense | |||||
| Macro IndicatorsiScaleWeakStable Strong |
Oral Antidiabetic Drugs Market Share (%), by Type, 2026
Go beyond the chart, access full insights & data tables
Request Free Sample ReportType 2 diabetes represented the largest share in the oral antidiabetic drugs market in 2025, driven primarily by the rapidly rising global prevalence of this condition and an increasing preference for oral therapies. This segment benefits from patient preference for minimally invasive, convenient management options aligned with chronic disease trends and improved supply chain efficiencies facilitating broad medication availability. For instance, the International Diabetes Federation highlights type 2 diabetes as a key global health challenge, reinforcing demand. The segment creates strategic opportunities for both established pharmaceutical companies and innovative entrants to develop effective, accessible treatments targeting a large patient population. Given ongoing epidemiological trends and sustained emphasis on oral regimen adherence, the type 2 diabetes segment is poised to maintain its leadership amid evolving healthcare frameworks and policy support.
Analysis by End User
Pharmacy stores held the largest share in the oral antidiabetic drugs market, supported by the global expansion of pharmacy networks which enhance accessibility and retail penetration. This growth reflects evolving consumer healthcare behaviors favoring convenience and regular access to medications for chronic type 2 diabetes management. Regulatory encouragement of pharmacy-based healthcare services and improved distribution logistics facilitate sustained patient adherence. The U.S. National Community Pharmacists Association illustrates that expanded pharmacy roles are integral to chronic disease care models, underscoring this segment's competitive advantage. This segment offers established firms and newcomers scalable retail channels to optimize patient reach and service innovation. The pharmacy store segment remains vital due to persistent efforts in decentralizing healthcare delivery and integrating digital health technologies within pharmacy networks.
Analysis by Drugs Class
Biguanides held the largest share in the oral antidiabetic drugs market, anchored by metformin’s continued dominance as the preferred first-line therapy for type 2 diabetes. This segment's leadership arises from the drug class’s proven efficacy, favorable safety profile, and broad clinical endorsement, including recommendations from the American Diabetes Association. The enduring clinical preference fosters stable demand and incentivizes pharmaceutical innovation focused on formulation and delivery enhancements. Additionally, the segment benefits from well-established manufacturing capabilities and robust physician familiarity. Strategic opportunities exist for companies to leverage metformin’s market presence while exploring novel biguanide derivatives or combination therapies. Sustained clinical guideline adherence and ongoing validation of biguanide benefits ensure this segment’s prominent role in treatment algorithms moving forward.
| Segment | Sub-Segment | Largest Segment | Fastest Growing |
|---|---|---|---|
| Type | Type 1 Diabetes, Type 2 diabetes | ||
| End User | Hospital, Pharmacy Store, Drug Store, Diabetics Treatment Centres, Others | ||
| Drugs Class | Sulfonylureas, Meglitinides, Repaglinide, Nateglinide, Biguanides, Alpha-glucosidase inhibitors |
Competitive Landscape and Market Positioning
The competitive landscape is marked by active developments, with these top firms enhancing their portfolios through strategic collaborations and sophisticated R&D efforts. Key players frequently introduce novel molecules and improved drug delivery mechanisms to address patient adherence and efficacy challenges. By integrating advanced biotechnology and digital health solutions, they continuously refine treatment paradigms and reinforce differentiation. Strategic alliances among these companies also enable accelerated access to emerging markets and innovative capabilities, thus intensifying competition while fostering an ecosystem conducive to innovation and responsiveness to evolving patient needs.
Strategic / Actionable Recommendations for Regional Players
North American companies should deepen cooperative endeavors with technology innovators and academic institutions to advance precision medicine approaches in diabetes care. Emphasizing patient-centric solutions and digital therapeutics can enhance treatment adherence and outcomes in this highly competitive market rich in healthcare infrastructure.
In the Asia Pacific region, tapping into fast-growing diabetes prevalence and expanding access via collaborations with local healthcare providers can unlock substantial opportunities. Embracing cost-effective, scalable production technologies and tailoring formulations to regional patient profiles will help capture unmet needs and build market trust.
European players are well-positioned to leverage their strong regulatory expertise and robust R&D ecosystems by focusing on next-generation oral therapies and combination regimens. Strengthening cross-border partnerships and embracing sustainable manufacturing practices will enhance competitiveness amid stringent market standards and growing focus on value-based care.
| Company | Market Share | Company Revenue | Revenue CAGR (%) | Product Portfolio | Geographic Presence | Innovation / R&D Focus | Strategic Developments |
|---|---|---|---|---|---|---|---|
| No companies available. | |||||||
Customize Your Report
Explore examples of how this report can be tailored to different research needs, including custom segments, additional topics or chapters, and related reports. Click a section of the wheel or its numbered marker to explore the available options.
Oral Antidiabetic Drugs Market — Custom Segments
| Segment | Sub-Segment |
|---|---|
| No segment data available. | |
Oral Antidiabetic Drugs Market — Custom TOC
| Custom Chapter | Chapter Details |
|---|---|
| No custom TOC data available. | |
Need a different cut of the data?
Request Custom ResearchFrequently Asked Questions
How will the oral antidiabetic drugs industry grow in terms of size and CAGR by 2035?
Which region emerges as the top contributor to the oral antidiabetic drugs market revenue?
Who is driving the fastest regional growth in the oral antidiabetic drugs sector?
How does type 2 diabetes segment fare in the oral antidiabetic drugs industry?
What share does pharmacy store segment hold in the oral antidiabetic drugs sector as of 2025?
Where is the biguanides segment seeing the strongest adoption within the oral antidiabetic drugs industry?
Who holds a significant market share in the oral antidiabetic drugs landscape?
Our Clients
"The team took the time to understand our specific business needs and delivered a report that was well aligned with our objectives. Their expertise and understanding of the industry were clearly reflected in the quality and relevance of the insights provided."
Siemens Healthcare
"Our experience in acquiring the research report has been excellent. The depth of analysis, and actionable insights provided have been extremely valuable in supporting our ongoing R&D efforts."
GC Biopharma
"The report offered a comprehensive view of the market trends. The in-depth segmentation and analysis of emerging opportunities gave us a better understanding of the market."
Medtronic
Our Research Team & Methodology
Every Fundamental Business Insights report is built by a dedicated vertical research team, validated through a structured primary-and-secondary methodology, and reviewed for accuracy before it reaches you.
Delivery
Published
Available
Support
- Market Size & Forecast
- Market Segmentation
- Regional Analysis
- Growth Drivers & Challenges
- Market Dynamics
- Competitive Landscape
- Company Profiles
- Competitive Benchmarking
- Mergers & Acquisitions
- Market Share Analysis or Key Company Strategies
- Value Chain Analysis
- Porter's Five Forces
- PESTLE Analysis
- Pricing Trends
- Supply-Demand Analysis
- Technology Landscape
- Regulatory Landscape
- Investment & Funding Landscape
- Emerging Opportunities
- Future Market Outlook